Your basement suite can trigger a Smith Manoeuvre™ rental strategy, even if you own only one property
Most homeowners treat rental income from their basement suite as supplemental cash flow, something that helps with the mortgage payment, maybe offsets property taxes. The money arrives, it goes into the general account, and expenses come out of that same pool. That structure leaves a legal tax advantage completely unused.
A basement suite is a rental business under the Income Tax Act. The income it generates is reportable. The expenses tied to that business are deductible. The interest you pay on debt used to fund those expenses is also deductible, provided the borrowed money was used for the purpose of earning income. What most people miss is that you can reverse-engineer this rule to convert your non-deductible mortgage debt into deductible investment debt without buying a second property.
The mechanism: gross rent pays down the mortgage, borrowed funds pay the expenses
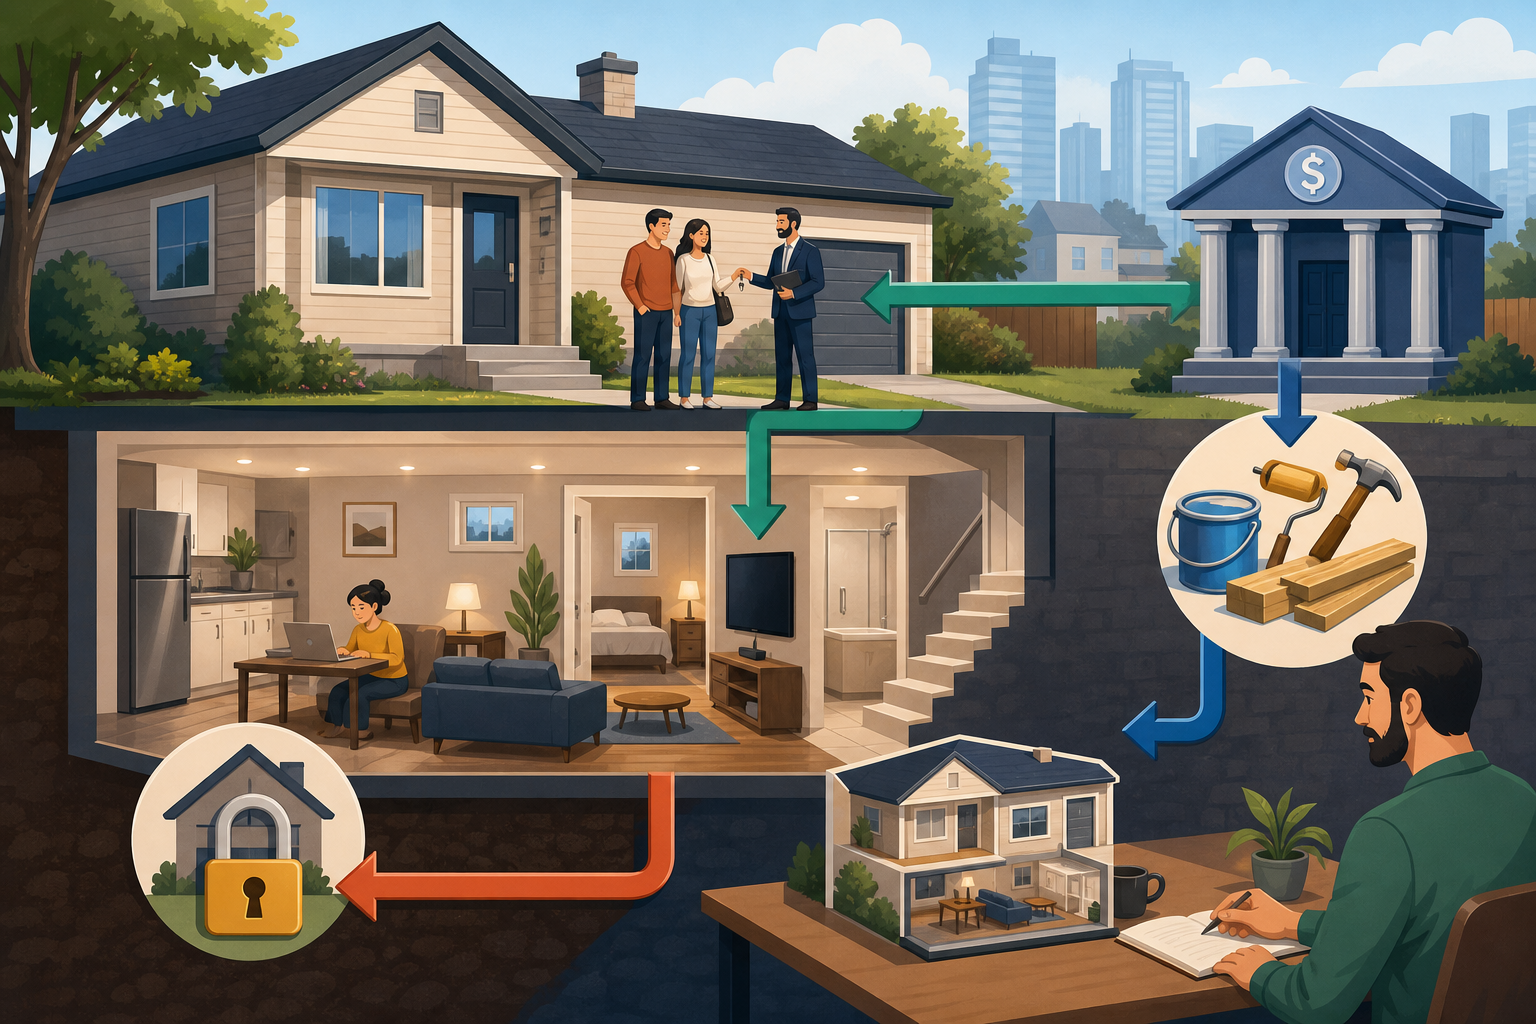
The strategy is called rental cash damming, and it runs on a simple mechanic. Instead of using rental income to pay expenses and then applying what's left to the mortgage, you flip the order. The gross rent goes directly to an extra principal payment on your primary mortgage. Then you use a Home Equity Line of Credit to pay for the suite's share of operating costs, utilities, repairs, property tax, insurance, anything tied to the rental space.
The interest on the HELOC portion used to pay rental expenses becomes tax-deductible. The primary mortgage shrinks faster. The deductible debt replaces the non-deductible debt at the exact rate rent allows. In Kelowna, where one-bedroom basement suites typically rent for $1,600 to $1,800, that substitution accelerates quickly.
Proportionality is mandatory, and the CRA enforces it
A basement suite typically represents 30% to 40% of the home's square footage. The Canada Revenue Agency requires you to split shared expenses by that ratio. If the suite is 35% of the home, you can deduct 35% of the heating bill, 35% of the property tax, 35% of the insurance premium. The rest is personal and stays non-deductible.
This means you cannot borrow the full amount of every household expense and call the interest deductible. You borrow only the portion allocated to the rental. If your annual property tax is $4,000 and the suite is 35% of the space, you borrow $1,400 for the suite's share. The HELOC interest on the remaining $2,600 of your personal property tax bill is non-deductible.
The rule applies to renovations as well. A new furnace serves the whole house. A soundproofing upgrade to the suite's ceiling serves only the rental. Proportional allocation determines what qualifies.
The structural requirement: a readvanceable mortgage
This strategy requires a mortgage product where the credit limit increases as the principal balance falls. RBC's Homeline Plan and Scotia's Total Equity Plan are common examples. Each time you make an extra principal payment using rental income, the HELOC portion of the product increases by the same amount. That rising credit limit is what you draw from to pay expenses.
Without this structure, the strategy stalls. A standard mortgage and a separate HELOC do not link. Paying down the mortgage does not automatically increase the line's availability, and manually refinancing every few months to capture equity is not practical.
Record-keeping separates this from audit risk
The CRA views cash damming with attention. The interest deduction depends entirely on proving that every dollar borrowed went to a rental-related invoice. This means separate accounts, clear paper trails, and no commingling. If you pull $800 from the HELOC to pay the plumber and $200 of that job was for the upstairs bathroom, only $600 qualifies.
Most rejections happen because the borrower used one account for personal and rental expenses, then tried to reconstruct the split later. The CRA denies the deduction when the records do not show a clear paper trail from the HELOC draw to the rental invoice.
The real benefit is speed, not just the deduction
By redirecting rent to principal reduction and replacing it with borrowed funds at a deductible rate, you retire the expensive non-deductible mortgage years ahead of schedule. In a high marginal tax bracket, 53.50% in BC for income over $240,716, the effective cost of the borrowed money drops by nearly half. The real speed advantage comes from this debt substitution, not just the yearly tax savings.
A basement suite operates as a tool that restructures how debt moves through your balance sheet when you set it up correctly. It is not passive income; it is an active reallocation of borrowed funds.



Most homeowners treat rental income from their basement suite as supplemental cash flow, something that helps with the mortgage payment, maybe offsets property taxes. The money arrives, it goes into the general account, and expenses come out of that same pool. That structure leaves a legal tax advantage completely unused.
A basement suite is a rental business under the Income Tax Act. The income it generates is reportable. The expenses tied to that business are deductible. The interest you pay on debt used to fund those expenses is also deductible, provided the borrowed money was used for the purpose of earning income. What most people miss is that you can reverse-engineer this rule to convert your non-deductible mortgage debt into deductible investment debt without buying a second property.
The mechanism: gross rent pays down the mortgage, borrowed funds pay the expenses
The strategy is called rental cash damming, and it runs on a simple mechanic. Instead of using rental income to pay expenses and then applying what's left to the mortgage, you flip the order. The gross rent goes directly to an extra principal payment on your primary mortgage. Then you use a Home Equity Line of Credit to pay for the suite's share of operating costs, utilities, repairs, property tax, insurance, anything tied to the rental space.
The interest on the HELOC portion used to pay rental expenses becomes tax-deductible. The primary mortgage shrinks faster. The deductible debt replaces the non-deductible debt at the exact rate rent allows. In Kelowna, where one-bedroom basement suites typically rent for $1,600 to $1,800, that substitution accelerates quickly.
Proportionality is mandatory, and the CRA enforces it
A basement suite typically represents 30% to 40% of the home's square footage. The Canada Revenue Agency requires you to split shared expenses by that ratio. If the suite is 35% of the home, you can deduct 35% of the heating bill, 35% of the property tax, 35% of the insurance premium. The rest is personal and stays non-deductible.
This means you cannot borrow the full amount of every household expense and call the interest deductible. You borrow only the portion allocated to the rental. If your annual property tax is $4,000 and the suite is 35% of the space, you borrow $1,400 for the suite's share. The HELOC interest on the remaining $2,600 of your personal property tax bill is non-deductible.
The rule applies to renovations as well. A new furnace serves the whole house. A soundproofing upgrade to the suite's ceiling serves only the rental. Proportional allocation determines what qualifies.
The structural requirement: a readvanceable mortgage
This strategy requires a mortgage product where the credit limit increases as the principal balance falls. RBC's Homeline Plan and Scotia's Total Equity Plan are common examples. Each time you make an extra principal payment using rental income, the HELOC portion of the product increases by the same amount. That rising credit limit is what you draw from to pay expenses.
Without this structure, the strategy stalls. A standard mortgage and a separate HELOC do not link. Paying down the mortgage does not automatically increase the line's availability, and manually refinancing every few months to capture equity is not practical.
Record-keeping separates this from audit risk
The CRA views cash damming with attention. The interest deduction depends entirely on proving that every dollar borrowed went to a rental-related invoice. This means separate accounts, clear paper trails, and no commingling. If you pull $800 from the HELOC to pay the plumber and $200 of that job was for the upstairs bathroom, only $600 qualifies.
Most rejections happen because the borrower used one account for personal and rental expenses, then tried to reconstruct the split later. The CRA denies the deduction when the records do not show a clear paper trail from the HELOC draw to the rental invoice.
The real benefit is speed, not just the deduction
By redirecting rent to principal reduction and replacing it with borrowed funds at a deductible rate, you retire the expensive non-deductible mortgage years ahead of schedule. In a high marginal tax bracket, 53.50% in BC for income over $240,716, the effective cost of the borrowed money drops by nearly half. The real speed advantage comes from this debt substitution, not just the yearly tax savings.
A basement suite operates as a tool that restructures how debt moves through your balance sheet when you set it up correctly. It is not passive income; it is an active reallocation of borrowed funds.
Sources
Read Next
Restructuring Your Mortgage Is Not a Rescue Mission
What a Mortgage Rate Discount Is Designed to Keep You From Noticing
Bank of Canada Cuts Won't Save Your Fixed Rate From U.S. Inflation
7 Debt Ratio Checks That Set Your Mortgage Ceiling Before Your Credit Score Matters