Why Shortening Your Amortization at Renewal Locks You Into the Wrong Payment Structure
When you renew a mortgage, shortening the amortization from 25 years to 15 years locks you into a significantly higher monthly payment that cannot be reduced without triggering a costly refinance, whereas maintaining a 25-year amortization while making voluntary prepayments achieves identical interest savings and equity building with the flexibility to adjust payments when income fluctuates. For most borrowers, especially those with variable income, this flexibility is worth more than the forced discipline of a shorter amortization.
This matters because of what happens when you go the other direction. At renewal, you can shorten the contractual amortization from 25 years to 15 years, which increases your required monthly payment and legally binds you to it for the next term. On a $400,000 mortgage at 5.25%, the 25-year payment is roughly $2,425/month. The 15-year payment is about $3,185/month. That's $760 more every month, mandatory.
The One-Way Valve
Once you renew into the shorter amortization, you own that payment. If your income drops, if your business has a slow quarter, if the BC Speculation and Vacancy Tax bill lands harder than expected, you cannot call the bank and ask to stretch the amortization back out. Lengthening the schedule after renewal is classified as a refinance under the B-20 Guidelines, which means a new stress test at the current qualifying rate, often around 5.25% plus 2%, or roughly 7.25%. If you don't qualify at that rate, you're stuck with the $3,185 payment or you're breaking the mortgage and eating a penalty.
The 25-year schedule with voluntary prepayments works the opposite way. You can pay the $3,185 every single month if you want, identical outcome, identical interest savings, identical equity build. But the contract only requires $2,425. The $760 difference is yours to control. You can pay it in January, skip it in March when a client is late, double it in June when a bonus clears. The schedule gives you a floor, not a ceiling.
The Forced Discipline Trap
The usual justification for the shorter amortization is psychological: "I won't actually make the extra payments unless the bank forces me." For some borrowers, that's true. If surplus cash consistently disappears into discretionary spending, the rigid structure does the work that willpower won't.
But for a business owner whose monthly revenue swings between $8,000 and $18,000 depending on seasonal demand, "forced discipline" is another term for "cash flow risk." The $760/month you locked in to "force savings" is the same $760 you might need in slow months when unexpected expenses arise or quarterly remittances are due.
The math on total interest paid is identical between the two paths if you actually use the prepayment privileges. A $400,000 mortgage paid off in 15 years costs the same in interest whether you do it with a 15-year amortization or a 25-year amortization and $760/month in voluntary prepayments. The only variable is control.
Where the Calculation Flips
Shortening the amortization makes sense in exactly one scenario: you have stable salaried income, zero likelihood of needing liquidity in the next five years, and a track record of not using prepayment options even when they're available. For everyone else, the voluntary route carries the same equity-building result with an insurance policy built in. That policy is the right to pay less in any given month without refinancing, without penalties, without requalifying.
The interest savings from shortening your amortization aren't free. You're paying for them with option value, the ability to adapt when conditions change. Keep the longer schedule. Pay it like the short one. Retain the escape hatch.


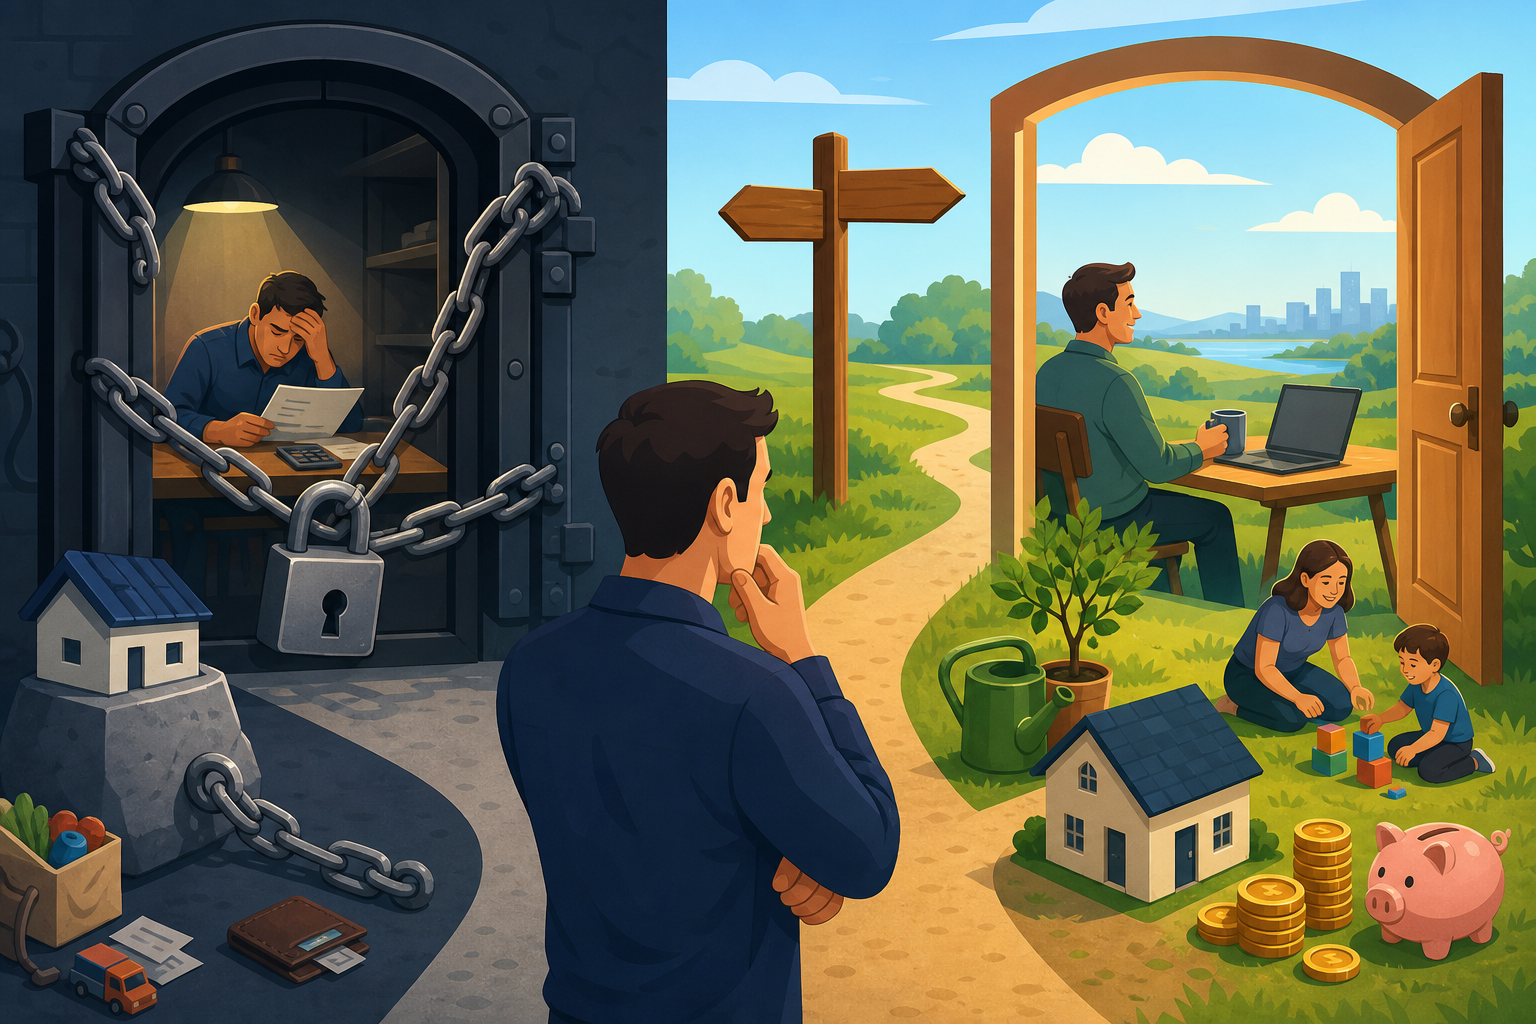

When you renew a mortgage, shortening the amortization from 25 years to 15 years locks you into a significantly higher monthly payment that cannot be reduced without triggering a costly refinance, whereas maintaining a 25-year amortization while making voluntary prepayments achieves identical interest savings and equity building with the flexibility to adjust payments when income fluctuates. For most borrowers, especially those with variable income, this flexibility is worth more than the forced discipline of a shorter amortization.
This matters because of what happens when you go the other direction. At renewal, you can shorten the contractual amortization from 25 years to 15 years, which increases your required monthly payment and legally binds you to it for the next term. On a $400,000 mortgage at 5.25%, the 25-year payment is roughly $2,425/month. The 15-year payment is about $3,185/month. That's $760 more every month, mandatory.
The One-Way Valve
Once you renew into the shorter amortization, you own that payment. If your income drops, if your business has a slow quarter, if the BC Speculation and Vacancy Tax bill lands harder than expected, you cannot call the bank and ask to stretch the amortization back out. Lengthening the schedule after renewal is classified as a refinance under the B-20 Guidelines, which means a new stress test at the current qualifying rate, often around 5.25% plus 2%, or roughly 7.25%. If you don't qualify at that rate, you're stuck with the $3,185 payment or you're breaking the mortgage and eating a penalty.
The 25-year schedule with voluntary prepayments works the opposite way. You can pay the $3,185 every single month if you want, identical outcome, identical interest savings, identical equity build. But the contract only requires $2,425. The $760 difference is yours to control. You can pay it in January, skip it in March when a client is late, double it in June when a bonus clears. The schedule gives you a floor, not a ceiling.
The Forced Discipline Trap
The usual justification for the shorter amortization is psychological: "I won't actually make the extra payments unless the bank forces me." For some borrowers, that's true. If surplus cash consistently disappears into discretionary spending, the rigid structure does the work that willpower won't.
But for a business owner whose monthly revenue swings between $8,000 and $18,000 depending on seasonal demand, "forced discipline" is another term for "cash flow risk." The $760/month you locked in to "force savings" is the same $760 you might need in slow months when unexpected expenses arise or quarterly remittances are due.
The math on total interest paid is identical between the two paths if you actually use the prepayment privileges. A $400,000 mortgage paid off in 15 years costs the same in interest whether you do it with a 15-year amortization or a 25-year amortization and $760/month in voluntary prepayments. The only variable is control.
Where the Calculation Flips
Shortening the amortization makes sense in exactly one scenario: you have stable salaried income, zero likelihood of needing liquidity in the next five years, and a track record of not using prepayment options even when they're available. For everyone else, the voluntary route carries the same equity-building result with an insurance policy built in. That policy is the right to pay less in any given month without refinancing, without penalties, without requalifying.
The interest savings from shortening your amortization aren't free. You're paying for them with option value, the ability to adapt when conditions change. Keep the longer schedule. Pay it like the short one. Retain the escape hatch.
Read Next
Restructuring Your Mortgage Is Not a Rescue Mission
What a Mortgage Rate Discount Is Designed to Keep You From Noticing
Bank of Canada Cuts Won't Save Your Fixed Rate From U.S. Inflation
7 Debt Ratio Checks That Set Your Mortgage Ceiling Before Your Credit Score Matters