Why Paying Off Your Mortgage With an Inheritance Is Often the Worst Thing You Can Do
A 58-year-old engineer in Burlington inherits $240,000. Her mortgage sits at $285,000, rate locked at 2.9% from 2021. She calls her bank, asks for the payoff statement, writes the cheque. The mortgage is gone. She owns the house free and clear. Six months later, her HVAC system dies. The replacement costs $18,000. She doesn't have it. She applies for a HELOC. The bank offers 7.2%. She has just traded a 2.9% mortgage for 7.2% debt to cover an expense she could have handled with cash if she hadn't buried the inheritance in her walls.
This mistake happens constantly because the advice to eliminate debt sounds like financial discipline. It isn't. Discipline would be asking what the capital does for you over the next twenty years, not what it does for your anxiety today.
The irreversibility problem
A mortgage payment is a reversible decision. You can always stop paying extra on principal. An inheritance applied to mortgage payoff is irreversible. Once that money enters your home equity, it is locked. You cannot access it without selling the property or borrowing it back, almost always at a higher rate than the one you just paid off. The $240,000 that could have covered emergencies, funded a TFSA for a decade, or kept in a high-interest savings account is now frozen in an asset that produces no income and cannot be touched without triggering a new transaction cost.
Most people holding mortgages below 3.5% are carrying the cheapest debt they will see in their lifetime. Using a windfall to eliminate it trades liquidity for a marginal interest saving that inflation is quietly eroding. A 2.9% mortgage in an environment where inflation currently stands at 3.0% is effectively free money. The real rate is near zero. Paying it off delivers a guaranteed 2.9% return, which sounds prudent until you realize the TFSA contribution room sitting unused could have compounded tax-free at historical equity returns closer to 7%, and a GIC with competitive rates beats the mortgage rate outright with zero risk.
The tax-sheltered opportunity you're ignoring
For 2026, the TFSA contribution limit is $7,000. Cumulative room for someone eligible since 2009 is $109,000. A $240,000 inheritance could max that account immediately, sheltering returns from tax forever. The alternative, paying down a mortgage that was already affordable, delivers no tax benefit and no flexibility. The TFSA grows. The home equity sits.
If the inheritance recipient has children, the RESP offers an immediate 20% return through the Canada Education Savings Grant on the first $2,500 contributed annually per child. That's a guaranteed return the mortgage payoff cannot match. The lifetime CESG cap is $7,200 per child. A windfall could trigger years of that match in one move.
When paying it off actually makes sense
The math flips when the mortgage rate is variable and climbing, or when the homeowner carries high-interest consumer debt. A line of credit at 8% or a credit card balance at 22% should be eliminated. The guaranteed return of killing that debt beats any realistic investment return. A fixed mortgage at 2.9% is subsidized capital in a world where borrowing costs have doubled.
The behavioral argument, some people cannot be trusted with liquid cash, has merit for a small subset of inheritors. If the windfall in a brokerage account becomes a spending temptation, locking it in home equity acts as forced savings. The cost of that approach, compounded over twenty years, runs into six figures.
The fragility you're creating
A household with a $1 million home and no mortgage but $12,000 in liquid savings is more fragile than a household with a $500,000 mortgage and $500,000 in diversified assets. The first household has no buffer. The second can weather job loss, health crises, and market downturns without triggering a forced sale. Equity does not pay for groceries. It does not cover property tax. It cannot be divided in an emergency.
An inheritance should build financial resilience--cash that covers months of expenses, investments that diversify risk, and accounts that compound tax-free. Debt-free sounds like security. In practice, it is often the opposite.


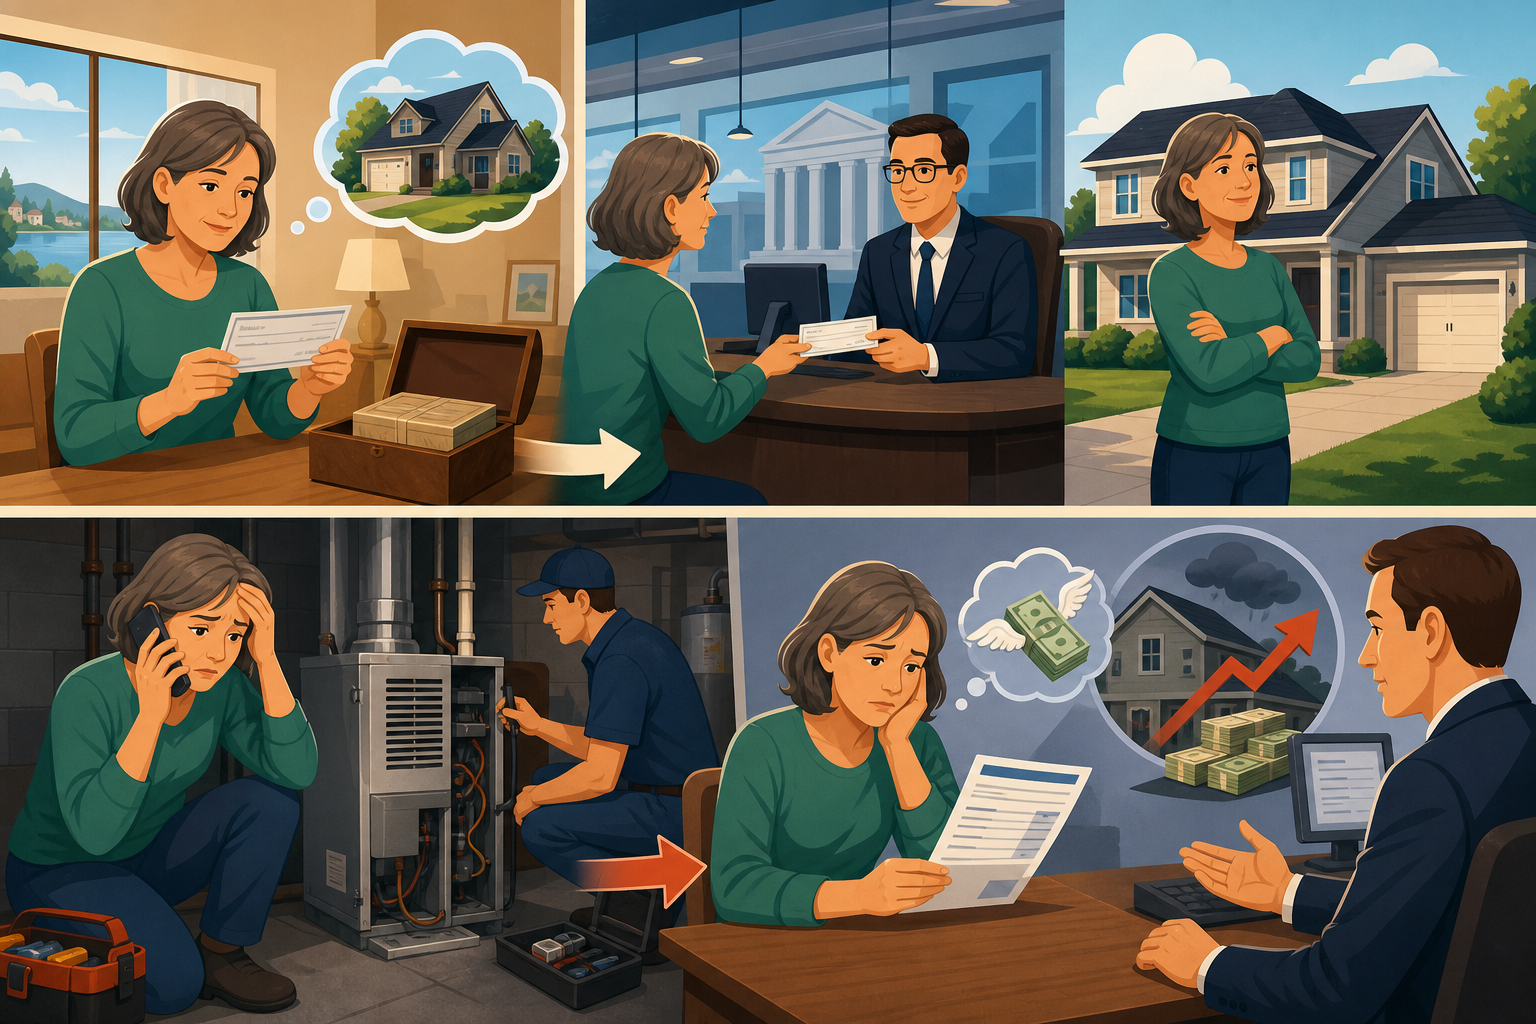

A 58-year-old engineer in Burlington inherits $240,000. Her mortgage sits at $285,000, rate locked at 2.9% from 2021. She calls her bank, asks for the payoff statement, writes the cheque. The mortgage is gone. She owns the house free and clear. Six months later, her HVAC system dies. The replacement costs $18,000. She doesn't have it. She applies for a HELOC. The bank offers 7.2%. She has just traded a 2.9% mortgage for 7.2% debt to cover an expense she could have handled with cash if she hadn't buried the inheritance in her walls.
This mistake happens constantly because the advice to eliminate debt sounds like financial discipline. It isn't. Discipline would be asking what the capital does for you over the next twenty years, not what it does for your anxiety today.
The irreversibility problem
A mortgage payment is a reversible decision. You can always stop paying extra on principal. An inheritance applied to mortgage payoff is irreversible. Once that money enters your home equity, it is locked. You cannot access it without selling the property or borrowing it back, almost always at a higher rate than the one you just paid off. The $240,000 that could have covered emergencies, funded a TFSA for a decade, or kept in a high-interest savings account is now frozen in an asset that produces no income and cannot be touched without triggering a new transaction cost.
Most people holding mortgages below 3.5% are carrying the cheapest debt they will see in their lifetime. Using a windfall to eliminate it trades liquidity for a marginal interest saving that inflation is quietly eroding. A 2.9% mortgage in an environment where inflation currently stands at 3.0% is effectively free money. The real rate is near zero. Paying it off delivers a guaranteed 2.9% return, which sounds prudent until you realize the TFSA contribution room sitting unused could have compounded tax-free at historical equity returns closer to 7%, and a GIC with competitive rates beats the mortgage rate outright with zero risk.
The tax-sheltered opportunity you're ignoring
For 2026, the TFSA contribution limit is $7,000. Cumulative room for someone eligible since 2009 is $109,000. A $240,000 inheritance could max that account immediately, sheltering returns from tax forever. The alternative, paying down a mortgage that was already affordable, delivers no tax benefit and no flexibility. The TFSA grows. The home equity sits.
If the inheritance recipient has children, the RESP offers an immediate 20% return through the Canada Education Savings Grant on the first $2,500 contributed annually per child. That's a guaranteed return the mortgage payoff cannot match. The lifetime CESG cap is $7,200 per child. A windfall could trigger years of that match in one move.
When paying it off actually makes sense
The math flips when the mortgage rate is variable and climbing, or when the homeowner carries high-interest consumer debt. A line of credit at 8% or a credit card balance at 22% should be eliminated. The guaranteed return of killing that debt beats any realistic investment return. A fixed mortgage at 2.9% is subsidized capital in a world where borrowing costs have doubled.
The behavioral argument, some people cannot be trusted with liquid cash, has merit for a small subset of inheritors. If the windfall in a brokerage account becomes a spending temptation, locking it in home equity acts as forced savings. The cost of that approach, compounded over twenty years, runs into six figures.
The fragility you're creating
A household with a $1 million home and no mortgage but $12,000 in liquid savings is more fragile than a household with a $500,000 mortgage and $500,000 in diversified assets. The first household has no buffer. The second can weather job loss, health crises, and market downturns without triggering a forced sale. Equity does not pay for groceries. It does not cover property tax. It cannot be divided in an emergency.
An inheritance should build financial resilience--cash that covers months of expenses, investments that diversify risk, and accounts that compound tax-free. Debt-free sounds like security. In practice, it is often the opposite.
Sources
Read Next
The OAS Clawback Is 15 Cents Per Dollar, Not 30 or 50
7 streaming services worth paying for in Canada, plus the credit cards that cut your bill
Ontario and B.C. First-Time Buyers Are Borrowing in Pairs, and the Cracks Are Starting to Show
Why Paying Off Your Mortgage First Can Cost You More Than the Interest Rate