Three Deductible Uses for Smith Manoeuvre™ Funds, and the Commingling Mistake That Voids Them
Most Smith Manoeuvre™ deductions are lost years before tax time, on the day borrowed money lands in an account that already holds something else. Nobody notices then. The problem shows up only if the CRA asks you to prove where the money went.
That question is the whole game. Section 20(1)(c) of the Income Tax Act lets you deduct interest only on money you borrowed and used with a reasonable expectation of earning income from a business or property. The CRA tests this by following each borrowed dollar to what it bought. Combined top marginal rates in BC and Ontario sit above 53%, so the deduction is a large part of why the strategy is worth its risk. Lose the trail and you still carry the debt, but the tax benefit is gone.
To see what's at stake, take an illustrative $100,000 drawn on the HELOC at an example rate of 6%. That's $6,000 of interest a year. At a 53% marginal rate, a clean deduction is worth about $3,180 back. A tangled one may be worth nothing.
Use one: non-registered investments
Open a brokerage account that only ever receives HELOC money. People skip this because they already have an account and opening another feels like paperwork. Moving borrowed funds into a mixed account is the most common reason claims get denied. A dedicated account makes your audit trail a single statement.
Pick holdings that pay income. Dividends, interest and distributions show the "reasonable expectation" the rule asks for. An asset that only promises capital gains, like a non-dividend stock or gold, invites a challenge. This gets skipped because growth stocks look more exciting on a chart.
Use two: rental property expenses
Pay rental property taxes, insurance and repairs directly from the HELOC. Then send the rent cheques to your home mortgage. Your non-deductible debt shrinks faster, and the interest on the HELOC draws for those expenses is deductible. Most investors skip this because paying rental bills out of rental income feels tidier. It costs them a deduction they could have had.
Use three: your own business
Put HELOC money into your corporation with documentation. That means a written shareholder loan or share subscription, a direct transfer from the HELOC to the business account, and records showing the company used the money to earn income. Owners skip the paperwork because it's their own company. The CRA still treats you and your corporation as two separate parties. It's also worth confirming with your accountant how the money gets used inside the company. Passive investment income above $50,000 a year starts eroding the small business deduction.
The mistakes that undo all three
Keep HELOC money out of your RRSP, TFSA and FHSA. Income earned inside those accounts is already sheltered, so the CRA won't let you deduct the interest on money borrowed to fund them. Plenty of people assume they can double up. They can't.
Never pay a personal bill from the investment HELOC, even once. A vacation, a car repair, a tuition payment: one personal draw turns a clean balance into a mixed one. From then on, every interest payment has to be split between the deductible and non-deductible portions, and you have to prove the split. If it does happen, set that amount up as its own separate line or pay it back right away, and tell your accountant.
Check that the numbers still work at higher rates. Most HELOCs in 2026 run around Prime + 0.50% to Prime + 1.00%. The strategy only makes sense while your after-tax interest cost stays below what the investments actually earn. Run that test again whenever prime moves.
If you only act on one item, make it the separate account. Every other rule here gets easier to prove once borrowed money has exactly one place to live.


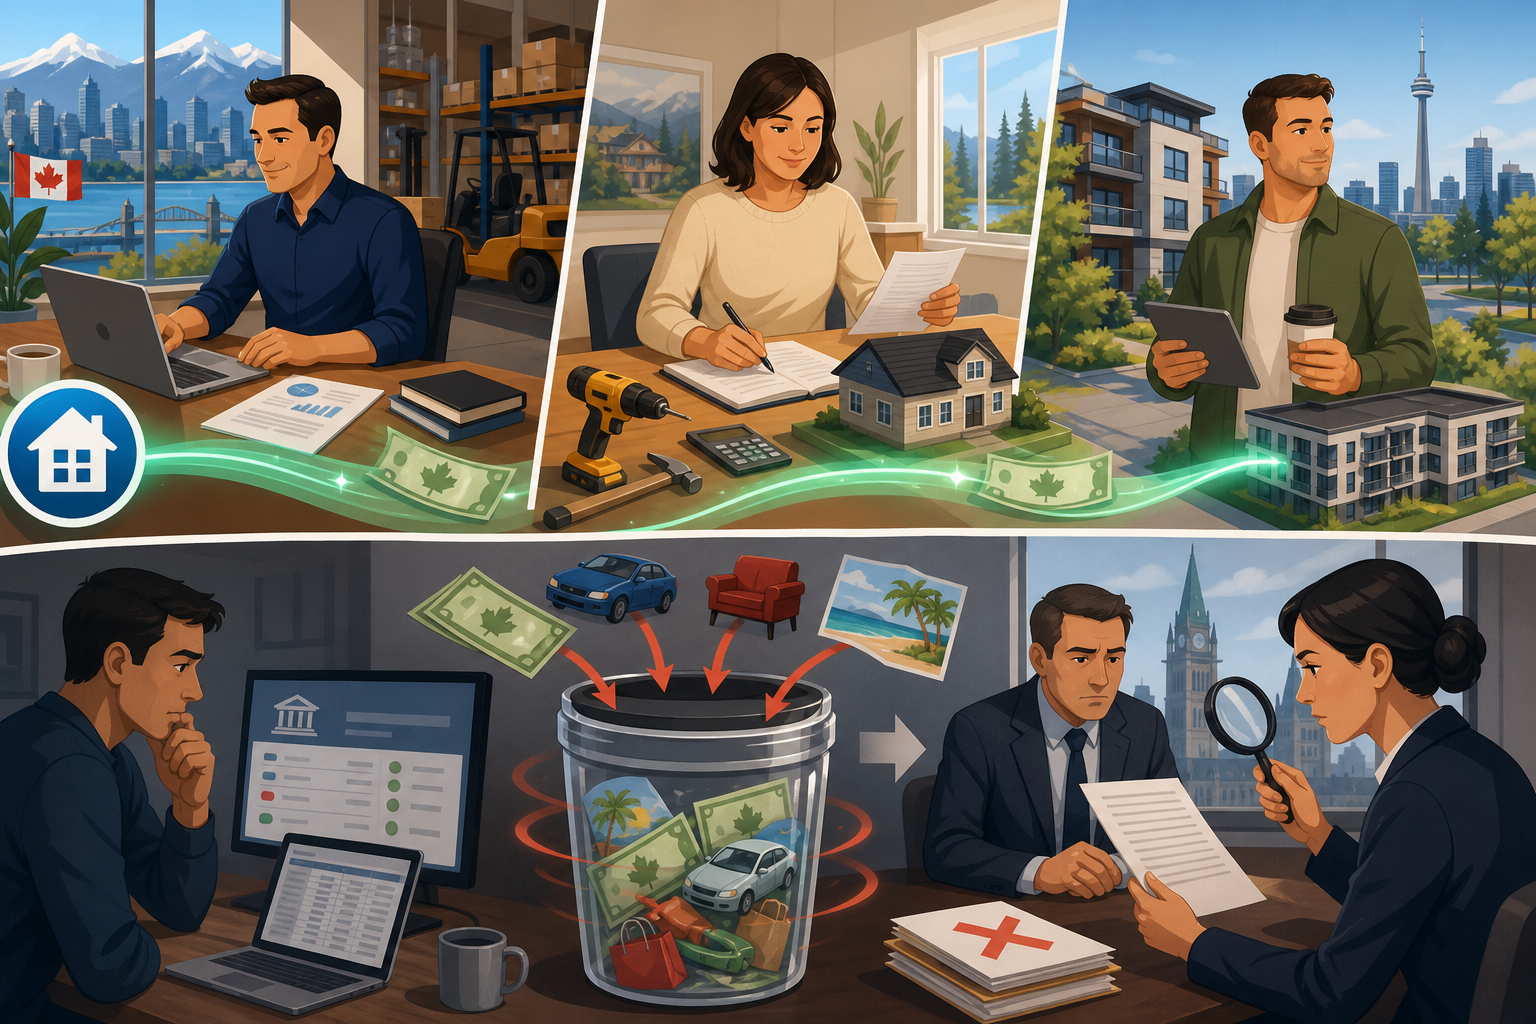

Most Smith Manoeuvre™ deductions are lost years before tax time, on the day borrowed money lands in an account that already holds something else. Nobody notices then. The problem shows up only if the CRA asks you to prove where the money went.
That question is the whole game. Section 20(1)(c) of the Income Tax Act lets you deduct interest only on money you borrowed and used with a reasonable expectation of earning income from a business or property. The CRA tests this by following each borrowed dollar to what it bought. Combined top marginal rates in BC and Ontario sit above 53%, so the deduction is a large part of why the strategy is worth its risk. Lose the trail and you still carry the debt, but the tax benefit is gone.
To see what's at stake, take an illustrative $100,000 drawn on the HELOC at an example rate of 6%. That's $6,000 of interest a year. At a 53% marginal rate, a clean deduction is worth about $3,180 back. A tangled one may be worth nothing.
Use one: non-registered investments
Open a brokerage account that only ever receives HELOC money. People skip this because they already have an account and opening another feels like paperwork. Moving borrowed funds into a mixed account is the most common reason claims get denied. A dedicated account makes your audit trail a single statement.
Pick holdings that pay income. Dividends, interest and distributions show the "reasonable expectation" the rule asks for. An asset that only promises capital gains, like a non-dividend stock or gold, invites a challenge. This gets skipped because growth stocks look more exciting on a chart.
Use two: rental property expenses
Pay rental property taxes, insurance and repairs directly from the HELOC. Then send the rent cheques to your home mortgage. Your non-deductible debt shrinks faster, and the interest on the HELOC draws for those expenses is deductible. Most investors skip this because paying rental bills out of rental income feels tidier. It costs them a deduction they could have had.
Use three: your own business
Put HELOC money into your corporation with documentation. That means a written shareholder loan or share subscription, a direct transfer from the HELOC to the business account, and records showing the company used the money to earn income. Owners skip the paperwork because it's their own company. The CRA still treats you and your corporation as two separate parties. It's also worth confirming with your accountant how the money gets used inside the company. Passive investment income above $50,000 a year starts eroding the small business deduction.
The mistakes that undo all three
Keep HELOC money out of your RRSP, TFSA and FHSA. Income earned inside those accounts is already sheltered, so the CRA won't let you deduct the interest on money borrowed to fund them. Plenty of people assume they can double up. They can't.
Never pay a personal bill from the investment HELOC, even once. A vacation, a car repair, a tuition payment: one personal draw turns a clean balance into a mixed one. From then on, every interest payment has to be split between the deductible and non-deductible portions, and you have to prove the split. If it does happen, set that amount up as its own separate line or pay it back right away, and tell your accountant.
Check that the numbers still work at higher rates. Most HELOCs in 2026 run around Prime + 0.50% to Prime + 1.00%. The strategy only makes sense while your after-tax interest cost stays below what the investments actually earn. Run that test again whenever prime moves.
If you only act on one item, make it the separate account. Every other rule here gets easier to prove once borrowed money has exactly one place to live.
Read Next
Restructuring Your Mortgage Is Not a Rescue Mission
What a Mortgage Rate Discount Is Designed to Keep You From Noticing
Bank of Canada Cuts Won't Save Your Fixed Rate From U.S. Inflation
7 Debt Ratio Checks That Set Your Mortgage Ceiling Before Your Credit Score Matters