The Mortgage Renewal Cliff Never Left, Canada Just Stopped Watching
Canada's mortgage crisis has shifted from a foreclosure threat to a hidden immobility trap: stress test rules prevent most borrowers renewing into higher rates from switching lenders, locking them into whatever terms their current bank offers while employment remains their only protection against default. As amortization extensions become routine and rental market dynamics tighten further, the underlying pressure continues to build beneath a veneer of stability.
The "cliff" was supposed to hit in 2023. Lenders braced for defaults. Policy analysts published worst-case scenarios. Then employment held, amortization extensions became routine, and arrears rose to 0.29%. The crisis didn't arrive on schedule, so the narrative shifted to "resilience" and "flexibility." That shift was premature.
The Shadow Problem: Mortgage Lock-In
The real damage isn't foreclosure. It's immobility. Because switching lenders at renewal triggers a new stress test, contract rate plus 200 basis points, or 5.25%, whichever is higher, most borrowers renewing into higher rates can't qualify elsewhere. They're stuck with their current lender, unable to shop, unable to move, unable to downsize even when it makes financial sense.
Consider a scenario in a market like Kelowna, where benchmark home prices remain high relative to local income. A homeowner with a $600,000 mortgage moving from 2.0% to 4.5% adds roughly $850 per month. If that borrower wants to switch lenders to find a better rate, they must re-qualify under the stress test at 6.5% or higher. Most won't pass. The lender knows it. The renewal offer reflects it.
This is the cliff the market stopped watching. A generation of homeowners is trapped in place, paying whatever rate their current bank sets because the alternative is being declined entirely.
Equity as Buffer, Not Solution
Many of these households still hold significant equity from the 2021, 2023 price surge. That provides a cushion the 2008 crisis didn't have. But equity doesn't pay the monthly bill. A household with $300,000 in home equity and $200 less per month in discretionary cash flow after renewal is wealthier on paper and poorer in practice. The equity matters when they sell. It doesn't help them afford the mortgage until then.
The Office of the Superintendent of Financial Institutions maintained the stress test specifically to prevent borrowers from over-leveraging. The test is working: defaults remain low. But it is also locking a large segment of the market into whatever terms their existing lender offers, preventing borrowers from shopping for better rates at renewal.
What the Labour Market Is Hiding
The reason the cliff hasn't triggered a wave of defaults is employment. Canadians are prioritizing mortgage payments over discretionary spending and other debt. Credit card balances are rising. Vacations are being skipped. Restaurant spending is down. The mortgage gets paid first.
That works as long as employment holds. The moment unemployment rises materially, the payment-prioritization strategy breaks. A borrower who can afford a $2,800 monthly payment by cutting everything else cannot afford it after a layoff, and the equity buffer only delays the problem until severance runs out.
The Financial Consumer Agency of Canada issued guidelines in July 2023 requiring lenders to contact at-risk borrowers proactively. Those conversations are happening. What they mostly produce is amortization extensions, significantly extending their amortization periods, lowering the monthly payment, and significantly increasing total interest paid. It's a deferral, not a fix.
The Rental Market Feedback Loop
In British Columbia, investors renewing at higher rates face provincial rent increase caps that prevent them from passing the full cost to tenants. The 2026 cap leaves many small-scale landlords cash-flow negative on properties they bought as income generators. Some will sell. Others will hold and subsidize the gap. Neither outcome adds supply or reduces pressure.
The cliff didn't disappear. The timeline stretched, the symptoms shifted, and the policy conversation moved on. The borrowers are still there, renewing into a rate environment their original qualifications never contemplated, with fewer options than the market pretends they have.


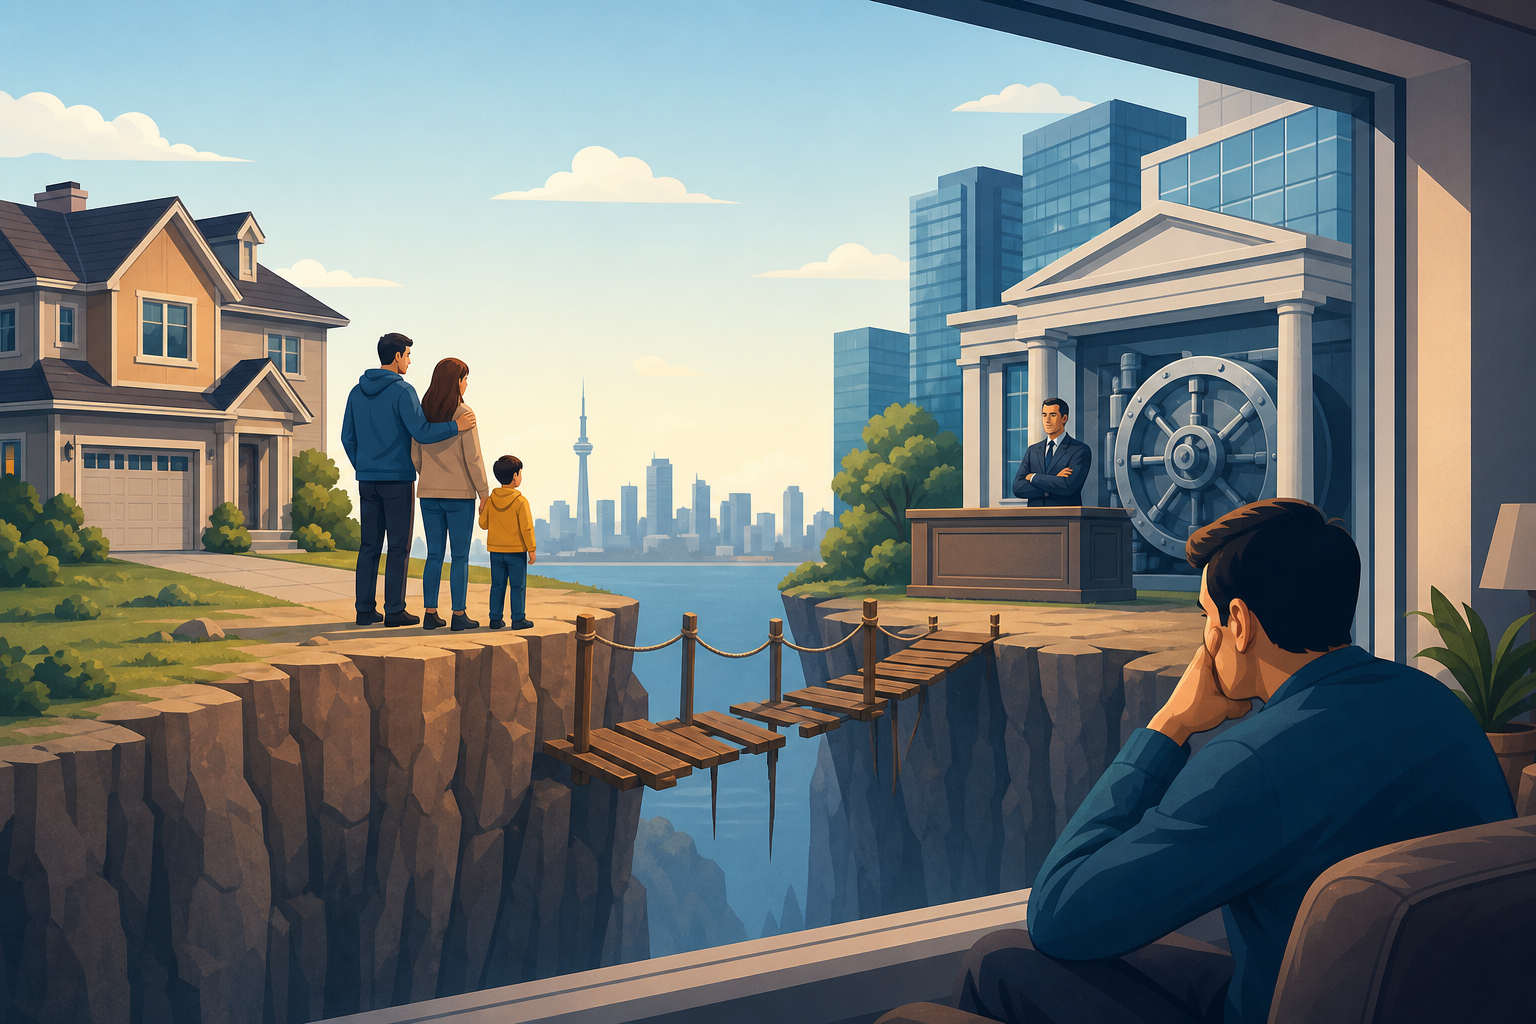

Canada's mortgage crisis has shifted from a foreclosure threat to a hidden immobility trap: stress test rules prevent most borrowers renewing into higher rates from switching lenders, locking them into whatever terms their current bank offers while employment remains their only protection against default. As amortization extensions become routine and rental market dynamics tighten further, the underlying pressure continues to build beneath a veneer of stability.
The "cliff" was supposed to hit in 2023. Lenders braced for defaults. Policy analysts published worst-case scenarios. Then employment held, amortization extensions became routine, and arrears rose to 0.29%. The crisis didn't arrive on schedule, so the narrative shifted to "resilience" and "flexibility." That shift was premature.
The Shadow Problem: Mortgage Lock-In
The real damage isn't foreclosure. It's immobility. Because switching lenders at renewal triggers a new stress test, contract rate plus 200 basis points, or 5.25%, whichever is higher, most borrowers renewing into higher rates can't qualify elsewhere. They're stuck with their current lender, unable to shop, unable to move, unable to downsize even when it makes financial sense.
Consider a scenario in a market like Kelowna, where benchmark home prices remain high relative to local income. A homeowner with a $600,000 mortgage moving from 2.0% to 4.5% adds roughly $850 per month. If that borrower wants to switch lenders to find a better rate, they must re-qualify under the stress test at 6.5% or higher. Most won't pass. The lender knows it. The renewal offer reflects it.
This is the cliff the market stopped watching. A generation of homeowners is trapped in place, paying whatever rate their current bank sets because the alternative is being declined entirely.
Equity as Buffer, Not Solution
Many of these households still hold significant equity from the 2021, 2023 price surge. That provides a cushion the 2008 crisis didn't have. But equity doesn't pay the monthly bill. A household with $300,000 in home equity and $200 less per month in discretionary cash flow after renewal is wealthier on paper and poorer in practice. The equity matters when they sell. It doesn't help them afford the mortgage until then.
The Office of the Superintendent of Financial Institutions maintained the stress test specifically to prevent borrowers from over-leveraging. The test is working: defaults remain low. But it is also locking a large segment of the market into whatever terms their existing lender offers, preventing borrowers from shopping for better rates at renewal.
What the Labour Market Is Hiding
The reason the cliff hasn't triggered a wave of defaults is employment. Canadians are prioritizing mortgage payments over discretionary spending and other debt. Credit card balances are rising. Vacations are being skipped. Restaurant spending is down. The mortgage gets paid first.
That works as long as employment holds. The moment unemployment rises materially, the payment-prioritization strategy breaks. A borrower who can afford a $2,800 monthly payment by cutting everything else cannot afford it after a layoff, and the equity buffer only delays the problem until severance runs out.
The Financial Consumer Agency of Canada issued guidelines in July 2023 requiring lenders to contact at-risk borrowers proactively. Those conversations are happening. What they mostly produce is amortization extensions, significantly extending their amortization periods, lowering the monthly payment, and significantly increasing total interest paid. It's a deferral, not a fix.
The Rental Market Feedback Loop
In British Columbia, investors renewing at higher rates face provincial rent increase caps that prevent them from passing the full cost to tenants. The 2026 cap leaves many small-scale landlords cash-flow negative on properties they bought as income generators. Some will sell. Others will hold and subsidize the gap. Neither outcome adds supply or reduces pressure.
The cliff didn't disappear. The timeline stretched, the symptoms shifted, and the policy conversation moved on. The borrowers are still there, renewing into a rate environment their original qualifications never contemplated, with fewer options than the market pretends they have.
Sources
Read Next
Restructuring Your Mortgage Is Not a Rescue Mission
What a Mortgage Rate Discount Is Designed to Keep You From Noticing
Bank of Canada Cuts Won't Save Your Fixed Rate From U.S. Inflation
7 Debt Ratio Checks That Set Your Mortgage Ceiling Before Your Credit Score Matters