The 70% failure rate advisors ignore: why heir preparation determines which families keep wealth
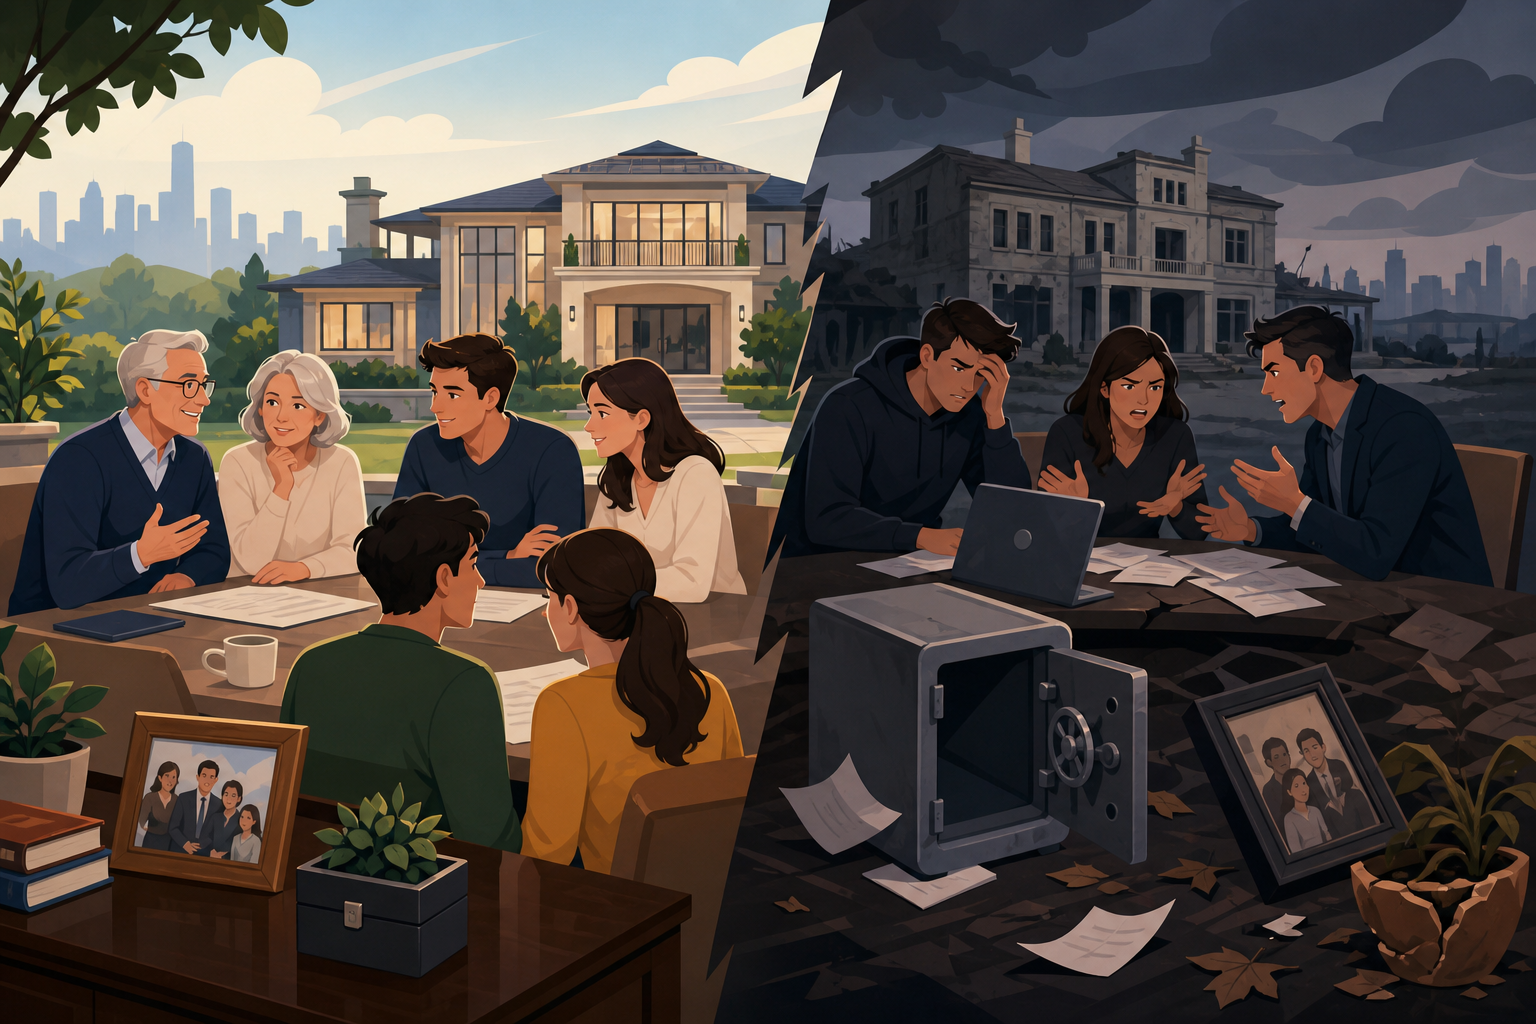
A 58-year-old client dies. The estate settles without drama. Assets transfer cleanly. Eighteen months later, the portfolio is gone and the children have hired someone else.
Most advisors have watched this happen. Few ask why. The assumption is that the new advisor offered lower fees or better technology or a relationship that felt more modern. All of that can be true. But the structural reason predates the death. The children were never part of the plan.
Canadian families are moving roughly $1 trillion to the next generation between 2023 and 2026. The advisory industry treats this as an asset-transfer event. Optimize the tax treatment, fund the insurance gap, update the will, confirm the beneficiaries. The technical work gets done. Nobody prepares the people receiving the money to handle what arrives. The statistic most cited in wealth management is this: 70% of intergenerational transfers fail by the second generation.
The failure is not usually market driven. Portfolios do not evaporate because the S&P dropped or because emerging markets disappointed. They evaporate because the family tears itself apart. A sibling dispute over the cottage becomes litigation. A disagreement about whether to sell the business becomes estrangement. The money gets liquidated to fund the fight or split up to end it, and the advisory relationship dies with the estate plan.
What actually causes the dissipation
Advisors focus on the deemed disposition problem at death. When a Canadian dies, the Canada Revenue Agency treats all capital property as sold at fair market value, triggering an immediate tax bill with no cash to pay it unless liquidity was planned in advance. Heirs who inherit $800,000 in unrealized gains and $50,000 in cash get a tax bill for $200,000 with no idea where the money is supposed to come from. That is a real problem, and advisors solve it well.
The deeper problem is relational. The heirs do not know what the wealth is for. They were never taught how to evaluate an investment, assess a manager, or make a decision as a group. One child thinks the money should fund early retirement. Another thinks it should go to charity. A third thinks the business should never have been sold in the first place. None of these positions were discussed when the parents were alive, because talking about money felt uncomfortable, and the advisor never forced the conversation.
Strategic philanthropy is being used by some advisors as a low-stakes rehearsal. A donor-advised fund lets heirs allocate $50,000 a year while the parents are still alive. The children argue over where to give, learn to negotiate, and make decisions with consequences but without catastrophic risk. When $2 million arrives later, the governance muscle already exists.
The retention gap is a relationship gap
Roughly 80% of heirs change advisors within a year of inheriting, while only about 20% of those who have already inherited retained their parent's advisor. The advisory industry describes this as a retention problem and builds CRM workflows to address it. Birthday cards to the children. Invitations to client events. Annual reviews that include the whole family. These moves help at the margin. The advisor who stays is the one who spent 20 years building trust with the parents and also years building it with the four children who will actually control the assets.
The clients who stay are the ones whose children were brought into the planning process years before the transfer. They attended planning meetings not as passive observers but as active participants in decisions. What does this family stand for? What do we want this money to accomplish? How do we make decisions when we disagree? Those are governance questions, and families without answers to them dissolve when the parents die.
High-net-worth families figured this out decades ago. Family offices start educating heirs in their twenties. Constitutions get written. Governance structures get formalized. This wealth is a shared responsibility, not an inheritance. A $2 million portfolio can fund the same intergenerational conflict as a $20 million one if nobody ever talked about what the money was for.



A 58-year-old client dies. The estate settles without drama. Assets transfer cleanly. Eighteen months later, the portfolio is gone and the children have hired someone else.
Most advisors have watched this happen. Few ask why. The assumption is that the new advisor offered lower fees or better technology or a relationship that felt more modern. All of that can be true. But the structural reason predates the death. The children were never part of the plan.
Canadian families are moving roughly $1 trillion to the next generation between 2023 and 2026. The advisory industry treats this as an asset-transfer event. Optimize the tax treatment, fund the insurance gap, update the will, confirm the beneficiaries. The technical work gets done. Nobody prepares the people receiving the money to handle what arrives. The statistic most cited in wealth management is this: 70% of intergenerational transfers fail by the second generation.
The failure is not usually market driven. Portfolios do not evaporate because the S&P dropped or because emerging markets disappointed. They evaporate because the family tears itself apart. A sibling dispute over the cottage becomes litigation. A disagreement about whether to sell the business becomes estrangement. The money gets liquidated to fund the fight or split up to end it, and the advisory relationship dies with the estate plan.
What actually causes the dissipation
Advisors focus on the deemed disposition problem at death. When a Canadian dies, the Canada Revenue Agency treats all capital property as sold at fair market value, triggering an immediate tax bill with no cash to pay it unless liquidity was planned in advance. Heirs who inherit $800,000 in unrealized gains and $50,000 in cash get a tax bill for $200,000 with no idea where the money is supposed to come from. That is a real problem, and advisors solve it well.
The deeper problem is relational. The heirs do not know what the wealth is for. They were never taught how to evaluate an investment, assess a manager, or make a decision as a group. One child thinks the money should fund early retirement. Another thinks it should go to charity. A third thinks the business should never have been sold in the first place. None of these positions were discussed when the parents were alive, because talking about money felt uncomfortable, and the advisor never forced the conversation.
Strategic philanthropy is being used by some advisors as a low-stakes rehearsal. A donor-advised fund lets heirs allocate $50,000 a year while the parents are still alive. The children argue over where to give, learn to negotiate, and make decisions with consequences but without catastrophic risk. When $2 million arrives later, the governance muscle already exists.
The retention gap is a relationship gap
Roughly 80% of heirs change advisors within a year of inheriting, while only about 20% of those who have already inherited retained their parent's advisor. The advisory industry describes this as a retention problem and builds CRM workflows to address it. Birthday cards to the children. Invitations to client events. Annual reviews that include the whole family. These moves help at the margin. The advisor who stays is the one who spent 20 years building trust with the parents and also years building it with the four children who will actually control the assets.
The clients who stay are the ones whose children were brought into the planning process years before the transfer. They attended planning meetings not as passive observers but as active participants in decisions. What does this family stand for? What do we want this money to accomplish? How do we make decisions when we disagree? Those are governance questions, and families without answers to them dissolve when the parents die.
High-net-worth families figured this out decades ago. Family offices start educating heirs in their twenties. Constitutions get written. Governance structures get formalized. This wealth is a shared responsibility, not an inheritance. A $2 million portfolio can fund the same intergenerational conflict as a $20 million one if nobody ever talked about what the money was for.
Sources
Read Next
The OAS Clawback Is 15 Cents Per Dollar, Not 30 or 50
7 streaming services worth paying for in Canada, plus the credit cards that cut your bill
Ontario and B.C. First-Time Buyers Are Borrowing in Pairs, and the Cracks Are Starting to Show
Why Paying Off Your Mortgage First Can Cost You More Than the Interest Rate