Selling Moneris to U.S. Private Equity Is Selling Canadian Payment Data
RBC and BMO just agreed to sell the infrastructure that touches one-third of all Canadian card transactions. The buyer is Francisco Partners, a San Francisco private equity firm with no track record of running critical national payment rails. The deal puts 3 billion transactions a year, and the metadata that travels with them, under U.S. legal jurisdiction.
Moneris isn't a boutique fintech startup. It processes payments for more than 325,000 merchant locations across Canada, from independent coffee shops in Whitehorse to national grocery chains. When you tap your card at a Toronto bodega or pay online for camping gear in Banff, there's a decent chance Moneris handles the authorization, settlement, and logging. The company has been a joint venture between RBC and BMO since 2000, which meant that at least the governance structure sat inside Canadian banks subject to Canadian oversight.
That changes when Francisco Partners takes control. The Investment Canada Act requires a "net benefit" review for foreign acquisitions over $1.326 billion. The Moneris deal almost certainly clears that threshold. But "net benefit" is a political calculus, not a technical one. The government can approve deals that concentrate risk as long as they pass a vague public-interest test.
The Jurisdiction Problem
A payment processor doesn't just move money. It creates a map. Every swipe, tap, or online checkout generates a timestamp, a merchant category code, a location, and an amount. Aggregated, that data shows not just what Canadians buy, but where they go, when they travel, which neighborhoods are gentrifying, which industries are contracting. Under Canadian law, specifically the Personal Information Protection and Electronic Documents Act (PIPEDA), that data has some protection. Under U.S. law, it sits within reach of the USA PATRIOT Act, which allows American authorities to demand records from U.S.-based entities even when the underlying customers are foreign nationals.
Francisco Partners is a private firm. They don't answer to voters. They answer to limited partners expecting double-digit returns. Private equity ownership of critical infrastructure historically means one thing: aggressive optimization. That could mean faster checkouts and better fraud detection. It could also mean data-mining Canadian spending patterns to feed proprietary credit models, marketing algorithms, or risk-assessment tools that Canadian regulators never approved and Canadian consumers never consented to.
Why the Banks Walked Away
RBC and BMO didn't sell Moneris because it was failing. They sold it because running a payment processor in 2026 is expensive, low-margin, and outside their strategic focus. The banks want to lend, not maintain POS hardware or negotiate interchange fees with Visa. That's a rational business decision. It's also a sovereignty decision dressed up as portfolio management.
When payment infrastructure shifts offshore, policy leverage shifts with it. If Ottawa wants to implement a digital services tax or tighten cross-border data rules, it now has to negotiate with a firm whose legal home is California. The systemic risk hasn't gone away. It's just moved to a different balance sheet, one with higher debt loads and shorter time horizons.
The comparison everyone avoids making is 2008. Not because this deal will cause a financial crisis, but because the structure is similar: critical infrastructure owned by entities optimized for short-term returns, with insufficient oversight of the second-order risks. Canadians don't use Moneris because they chose it. They use it because their corner store chose it. When that choice gets made in a San Francisco boardroom instead of a Toronto one, the feedback loop breaks.
The federal government has 75 days to decide whether this deal serves the national interest. The question isn't whether Francisco Partners will keep the lights on. They will. The question is what happens to the data, who gets to see it, and whether Canadians will even know when it moves.


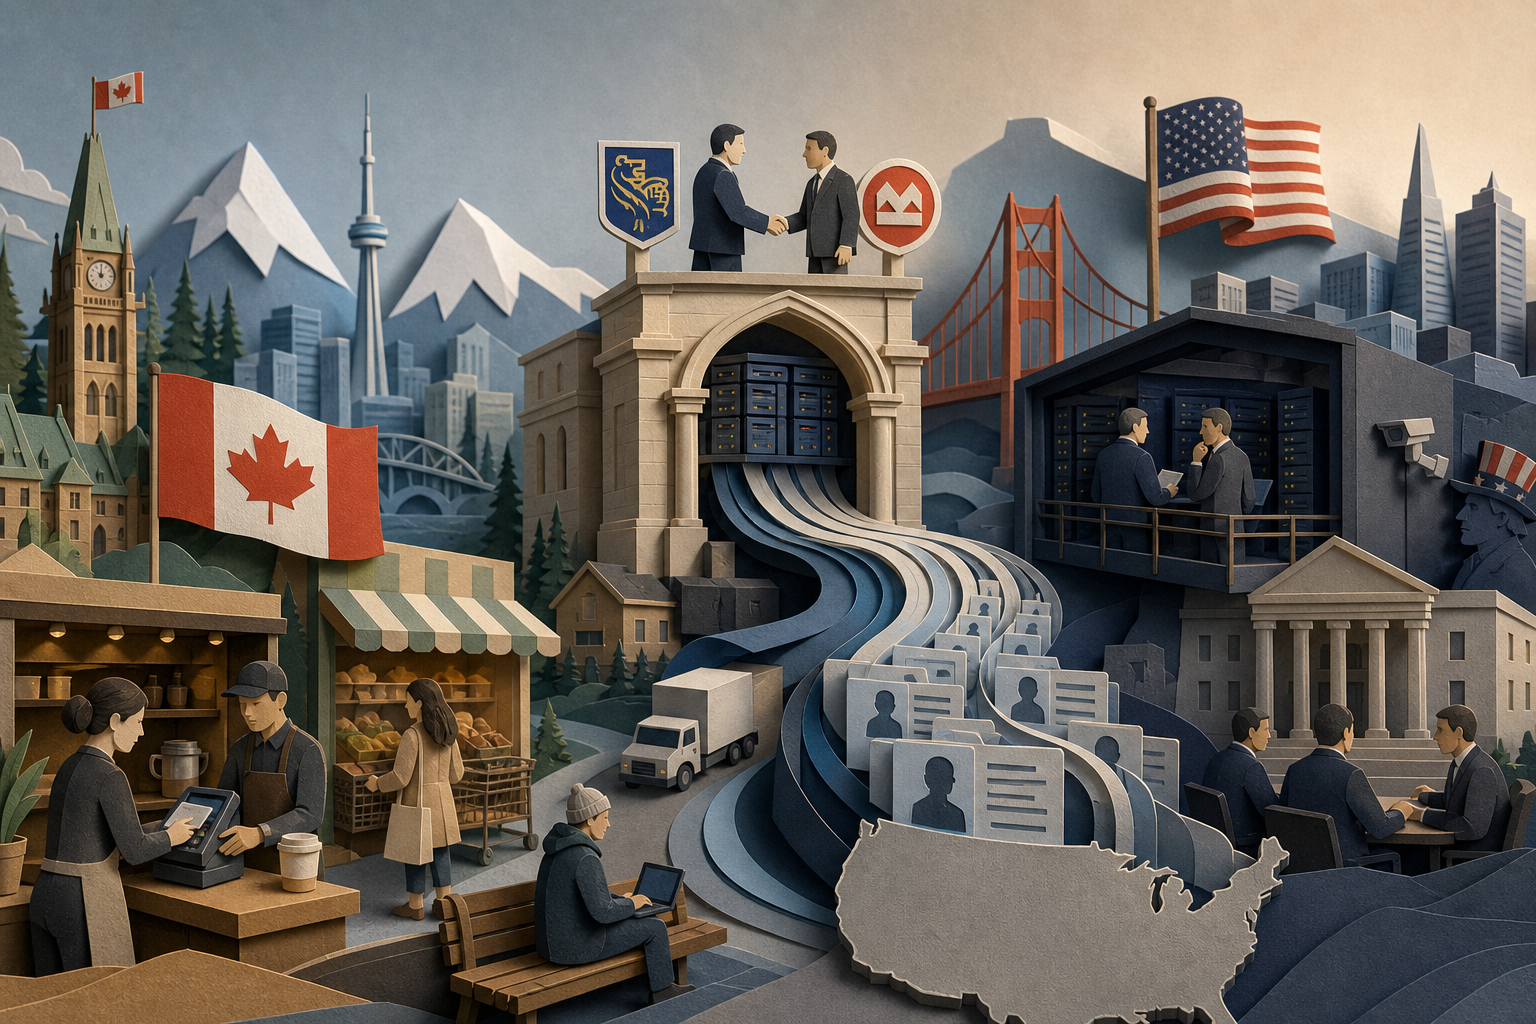

RBC and BMO just agreed to sell the infrastructure that touches one-third of all Canadian card transactions. The buyer is Francisco Partners, a San Francisco private equity firm with no track record of running critical national payment rails. The deal puts 3 billion transactions a year, and the metadata that travels with them, under U.S. legal jurisdiction.
Moneris isn't a boutique fintech startup. It processes payments for more than 325,000 merchant locations across Canada, from independent coffee shops in Whitehorse to national grocery chains. When you tap your card at a Toronto bodega or pay online for camping gear in Banff, there's a decent chance Moneris handles the authorization, settlement, and logging. The company has been a joint venture between RBC and BMO since 2000, which meant that at least the governance structure sat inside Canadian banks subject to Canadian oversight.
That changes when Francisco Partners takes control. The Investment Canada Act requires a "net benefit" review for foreign acquisitions over $1.326 billion. The Moneris deal almost certainly clears that threshold. But "net benefit" is a political calculus, not a technical one. The government can approve deals that concentrate risk as long as they pass a vague public-interest test.
The Jurisdiction Problem
A payment processor doesn't just move money. It creates a map. Every swipe, tap, or online checkout generates a timestamp, a merchant category code, a location, and an amount. Aggregated, that data shows not just what Canadians buy, but where they go, when they travel, which neighborhoods are gentrifying, which industries are contracting. Under Canadian law, specifically the Personal Information Protection and Electronic Documents Act (PIPEDA), that data has some protection. Under U.S. law, it sits within reach of the USA PATRIOT Act, which allows American authorities to demand records from U.S.-based entities even when the underlying customers are foreign nationals.
Francisco Partners is a private firm. They don't answer to voters. They answer to limited partners expecting double-digit returns. Private equity ownership of critical infrastructure historically means one thing: aggressive optimization. That could mean faster checkouts and better fraud detection. It could also mean data-mining Canadian spending patterns to feed proprietary credit models, marketing algorithms, or risk-assessment tools that Canadian regulators never approved and Canadian consumers never consented to.
Why the Banks Walked Away
RBC and BMO didn't sell Moneris because it was failing. They sold it because running a payment processor in 2026 is expensive, low-margin, and outside their strategic focus. The banks want to lend, not maintain POS hardware or negotiate interchange fees with Visa. That's a rational business decision. It's also a sovereignty decision dressed up as portfolio management.
When payment infrastructure shifts offshore, policy leverage shifts with it. If Ottawa wants to implement a digital services tax or tighten cross-border data rules, it now has to negotiate with a firm whose legal home is California. The systemic risk hasn't gone away. It's just moved to a different balance sheet, one with higher debt loads and shorter time horizons.
The comparison everyone avoids making is 2008. Not because this deal will cause a financial crisis, but because the structure is similar: critical infrastructure owned by entities optimized for short-term returns, with insufficient oversight of the second-order risks. Canadians don't use Moneris because they chose it. They use it because their corner store chose it. When that choice gets made in a San Francisco boardroom instead of a Toronto one, the feedback loop breaks.
The federal government has 75 days to decide whether this deal serves the national interest. The question isn't whether Francisco Partners will keep the lights on. They will. The question is what happens to the data, who gets to see it, and whether Canadians will even know when it moves.
Read Next
How to Eliminate Bridge Financing by Controlling Your Closing Dates
How to position your portfolio for a decade of below-average stock market returns
The Government's 'Productivity Deduction' Is a Rebrand, Not a Reform
Pay Down Your House Before Your Rental: The Tax Math Real Estate Investors Miss