Manulife Withdraws Leveraged Insurance Product Under Regulatory Pressure
Manulife Withdraws Leveraged Insurance Product Under Regulatory Pressure
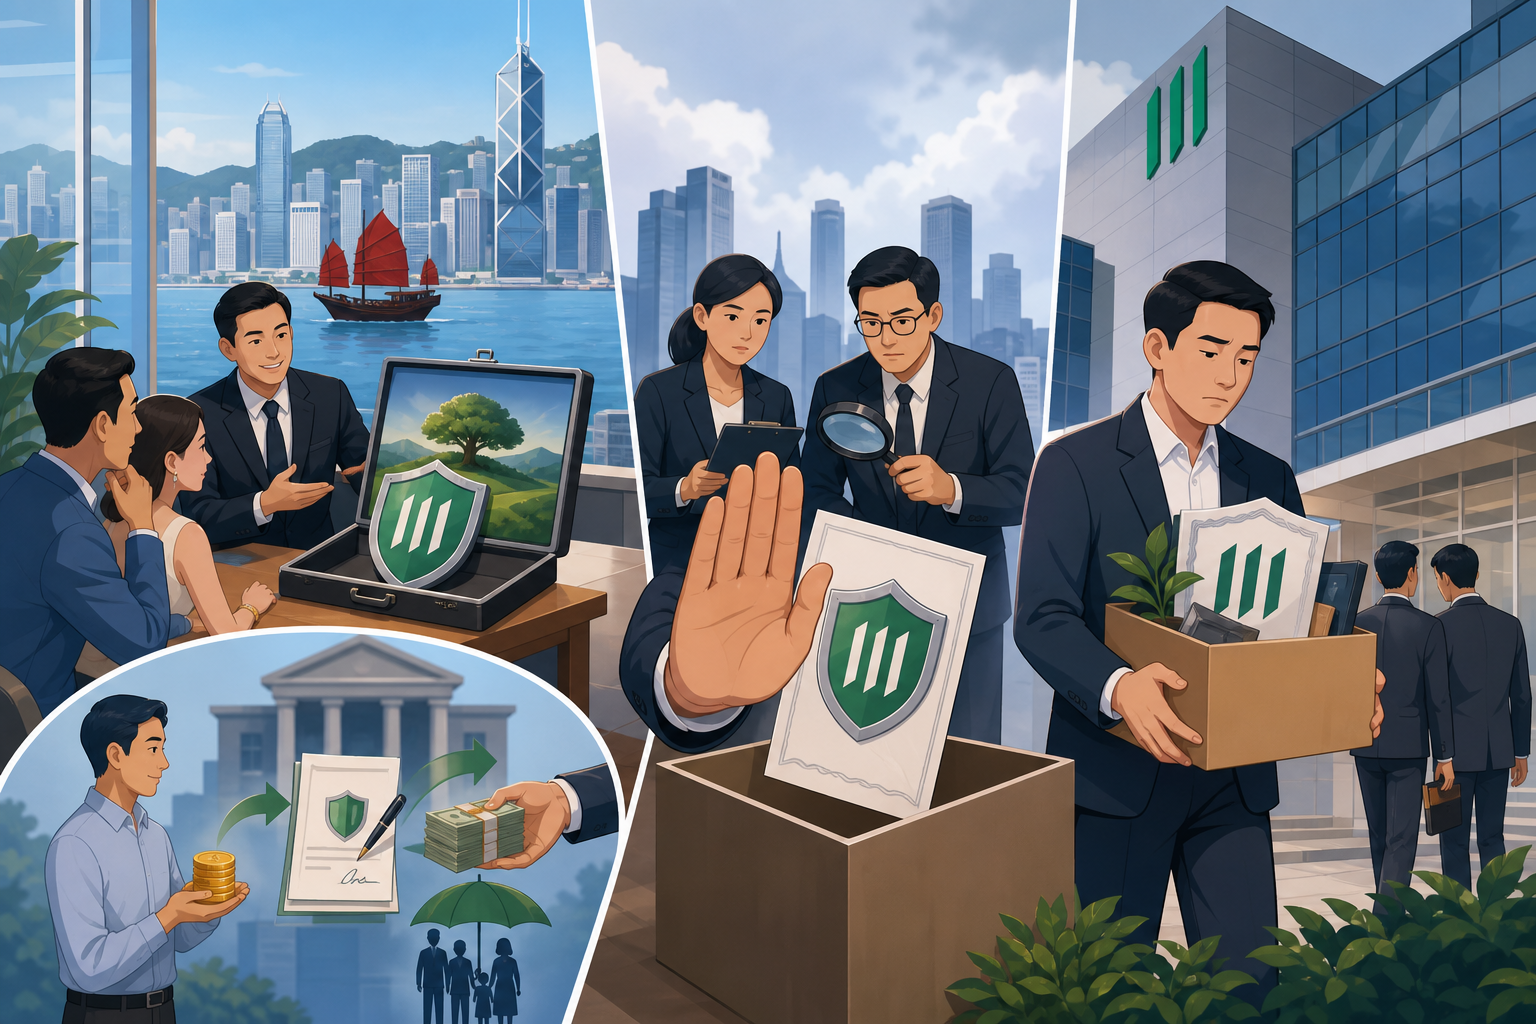
The product had been on the market for less than eighteen months. Manulife Financial Corp. sold it to high-net-worth clients across Hong Kong as a premium financing vehicle, borrow against the policy, pocket the spread between what the policy credits and what the loan costs, repeat. By March 2025, the Hong Kong Insurance Authority and the Hong Kong Monetary Authority had conducted three joint inspections of intermediaries selling these structures. Manulife withdrew the product in June 2026.
The mechanics were straightforward. A client paid 10% of the premium. A bank lent the other 90%, using the policy itself as collateral. If the policy's dividend rate ran higher than the loan interest rate, the client extracted the difference as income without putting up the full capital. For years, that math worked. The US Federal Reserve kept rates near zero. Hong Kong, pegged to the dollar, followed. Insurers competed on projected crediting rates, some publishing illustrations above 5% while loan rates sat in the low twos.
The structure fell apart in 2023. The Fed raised rates faster than it had in four decades. By mid-2024, the cost of borrowing for these policies had risen sharply, while actual crediting rates, non-guaranteed, began drifting lower as insurers reset their portfolios. Clients who took out policies in 2022 found themselves paying more in interest than they were earning in dividends. The carry trade reversed.
Why Manulife moved first
Regulators did not issue an outright ban. The IA's 2024 annual report notes 47 onsite inspections of intermediaries throughout the year, focusing on whether agents disclosed the leverage risks and the non-guaranteed nature of dividend projections. The language was careful. The message was clear.
Manulife's withdrawal is reputational de-risking. The company is avoiding a cycle where clients sue over shortfalls, regulators open formal investigations, and the brand takes years of damage in a market where trust drives high-net-worth flows. Other global insurers, Prudential, AIA, have quietly stopped illustrating premium financing scenarios in sales materials. These products were marketed as wealth preservation tools for sophisticated investors. What they introduced was margin risk. A leveraged policy behaves like a margin loan on equities: small moves in the spread get amplified by the size of the borrowed base. Clients who understood that dynamic were rare. Agents who explained it clearly were rarer.
What replaces it
Manulife has not exited the high-net-worth segment. The company still sells whole-life and universal life policies in Hong Kong, but without the financing pitch. The new framing is legacy planning and estate transfer. Projected returns are lower. Upfront disclosure is longer.
The broader shift across the Hong Kong market is from speculation back to protection. The IA's 2025 guidelines push insurers toward products where the benefit is explicit, death benefit, critical illness coverage, guaranteed annuity payments, and away from structures where the value depends on interest rate forecasts and non-guaranteed dividends compounding exactly as illustrated.
If global interest rates fall sharply in late 2026 or 2027, demand for leveraged insurance may resurface. Insurers will probably relaunch these products with tighter loan-to-value caps, clearer risk disclosures, and stress-tested illustrations. The appetite among mainland Chinese investors for Hong Kong dollar or US dollar vehicles remains strong. But the window where premium financing could be sold as low-risk carry has closed. What comes next will require the client to actually understand what leverage does when the math stops working in their favor.



Manulife Withdraws Leveraged Insurance Product Under Regulatory Pressure
The product had been on the market for less than eighteen months. Manulife Financial Corp. sold it to high-net-worth clients across Hong Kong as a premium financing vehicle, borrow against the policy, pocket the spread between what the policy credits and what the loan costs, repeat. By March 2025, the Hong Kong Insurance Authority and the Hong Kong Monetary Authority had conducted three joint inspections of intermediaries selling these structures. Manulife withdrew the product in June 2026.
The mechanics were straightforward. A client paid 10% of the premium. A bank lent the other 90%, using the policy itself as collateral. If the policy's dividend rate ran higher than the loan interest rate, the client extracted the difference as income without putting up the full capital. For years, that math worked. The US Federal Reserve kept rates near zero. Hong Kong, pegged to the dollar, followed. Insurers competed on projected crediting rates, some publishing illustrations above 5% while loan rates sat in the low twos.
The structure fell apart in 2023. The Fed raised rates faster than it had in four decades. By mid-2024, the cost of borrowing for these policies had risen sharply, while actual crediting rates, non-guaranteed, began drifting lower as insurers reset their portfolios. Clients who took out policies in 2022 found themselves paying more in interest than they were earning in dividends. The carry trade reversed.
Why Manulife moved first
Regulators did not issue an outright ban. The IA's 2024 annual report notes 47 onsite inspections of intermediaries throughout the year, focusing on whether agents disclosed the leverage risks and the non-guaranteed nature of dividend projections. The language was careful. The message was clear.
Manulife's withdrawal is reputational de-risking. The company is avoiding a cycle where clients sue over shortfalls, regulators open formal investigations, and the brand takes years of damage in a market where trust drives high-net-worth flows. Other global insurers, Prudential, AIA, have quietly stopped illustrating premium financing scenarios in sales materials. These products were marketed as wealth preservation tools for sophisticated investors. What they introduced was margin risk. A leveraged policy behaves like a margin loan on equities: small moves in the spread get amplified by the size of the borrowed base. Clients who understood that dynamic were rare. Agents who explained it clearly were rarer.
What replaces it
Manulife has not exited the high-net-worth segment. The company still sells whole-life and universal life policies in Hong Kong, but without the financing pitch. The new framing is legacy planning and estate transfer. Projected returns are lower. Upfront disclosure is longer.
The broader shift across the Hong Kong market is from speculation back to protection. The IA's 2025 guidelines push insurers toward products where the benefit is explicit, death benefit, critical illness coverage, guaranteed annuity payments, and away from structures where the value depends on interest rate forecasts and non-guaranteed dividends compounding exactly as illustrated.
If global interest rates fall sharply in late 2026 or 2027, demand for leveraged insurance may resurface. Insurers will probably relaunch these products with tighter loan-to-value caps, clearer risk disclosures, and stress-tested illustrations. The appetite among mainland Chinese investors for Hong Kong dollar or US dollar vehicles remains strong. But the window where premium financing could be sold as low-risk carry has closed. What comes next will require the client to actually understand what leverage does when the math stops working in their favor.
Sources
Read Next
The OAS Clawback Is 15 Cents Per Dollar, Not 30 or 50
7 streaming services worth paying for in Canada, plus the credit cards that cut your bill
Ontario and B.C. First-Time Buyers Are Borrowing in Pairs, and the Cracks Are Starting to Show
Why Paying Off Your Mortgage First Can Cost You More Than the Interest Rate