Lock In Your Line of Credit While You Still Qualify: Why Income Timing Matters More Than Equity
A Kelowna couple owns their home outright. $1.8 million in equity, no mortgage. The husband retires in March, and by June they need $75,000 to replace the roof and retrofit an accessible bathroom. They apply for a line of credit. The bank says no.
The rejection isn't about collateral. The house appraises fine. The couple simply no longer earns enough monthly income to pass the stress test, which requires them to qualify at 5.25% even though the actual rate is closer to 5.5%. Their CPP, OAS, and modest RRSP withdrawals total $4,200 a month. Under federal Debt Service Ratio rules, that's enough for about $40,000 of revolving credit. The bank assumed their equity would support $150,000.
A couple with monthly income of $4,200 can secure a $40,000 line of credit but not the $150,000 they expected. This happens because banks lend against the paycheque, not the house. You must act before the paycheque stops.
Banks lend against cash flow, not net worth
Canadian lenders qualify you on Gross Debt Service (GDS) and Total Debt Service (TDS) ratios. The stress test floor, currently 5.25%, means you must prove you could still afford the payments if rates spiked. A borrower earning $120,000 a year qualifies for far more credit than a retiree pulling $50,000 from pensions and registered accounts, even when the retiree has ten times the assets.
The Office of the Superintendent of Financial Institutions enforces this through its B-20 guidelines. The system is designed to protect borrowers from over-leverage, but it creates a paradox for asset-rich, income-light households. You can own a $2 million house free and clear and still fail to qualify for a $100,000 HELOC once your T4 income disappears.
The zero-cost safety net
A Home Equity Line of Credit costs nothing if you never use it. It sits at a zero balance, incurs no interest, and requires no monthly payment until you draw on it. The cost to set one up, legal fees, appraisal, registration, runs $800 to $2,000 depending on the lender and whether you're bundling it with a mortgage renewal. That's the full price of the insurance policy.
Federal rules cap the revolving portion of a HELOC at 65% of your home's value. On an $800,000 Kelowna home, that's $520,000 of potential access. Once registered, the limit stays in place regardless of what happens to your income, your job, or your health. The line remains open as long as you don't default or trigger a readvanceable mortgage clause that reduces the limit as you pay down a mortgage.
The best time to secure this is during a mortgage renewal or a purchase. Most lenders will register the charge as part of the transaction, which saves you a separate set of fees. If you're three years from retirement and refinancing anyway, this is when you lock it in.
What it actually buys you
The most common use isn't lifestyle spending. It's sequence-of-return protection. A retiree forced to sell equities in a down market to pay for a new furnace or property taxes locks in losses that compound over the rest of their retirement. A HELOC lets you cover the expense with borrowed funds, wait for the market to recover, then repay the line from the portfolio at a better valuation.
Estate planning is the other big one. Immediate estate costs, probate fees, final tax bills, property maintenance while the estate settles, often come due before the executor can liquidate RRSPs or investment accounts. A line of credit provides the liquidity to pay those bills without triggering a forced withdrawal at the worst possible tax rate.
Aging-in-place modifications are the third. Kelowna's housing stock skews older. A house built in 1985 wasn't designed for someone using a walker. Installing a stair lift, widening doorways, or retrofitting a main-floor bathroom runs $30,000 to $80,000. If you're already retired and living on $55,000 a year, most banks won't lend you that money. If you set up the line five years earlier, the money is already there.
The retirees who regret this decision are the ones who wait until they need the credit to apply for it. By then, the underwriter sees need as risk, and the application gets declined. The ones who sleep well are the ones who secured the line while they were still flourishing and let it sit unused for a decade.


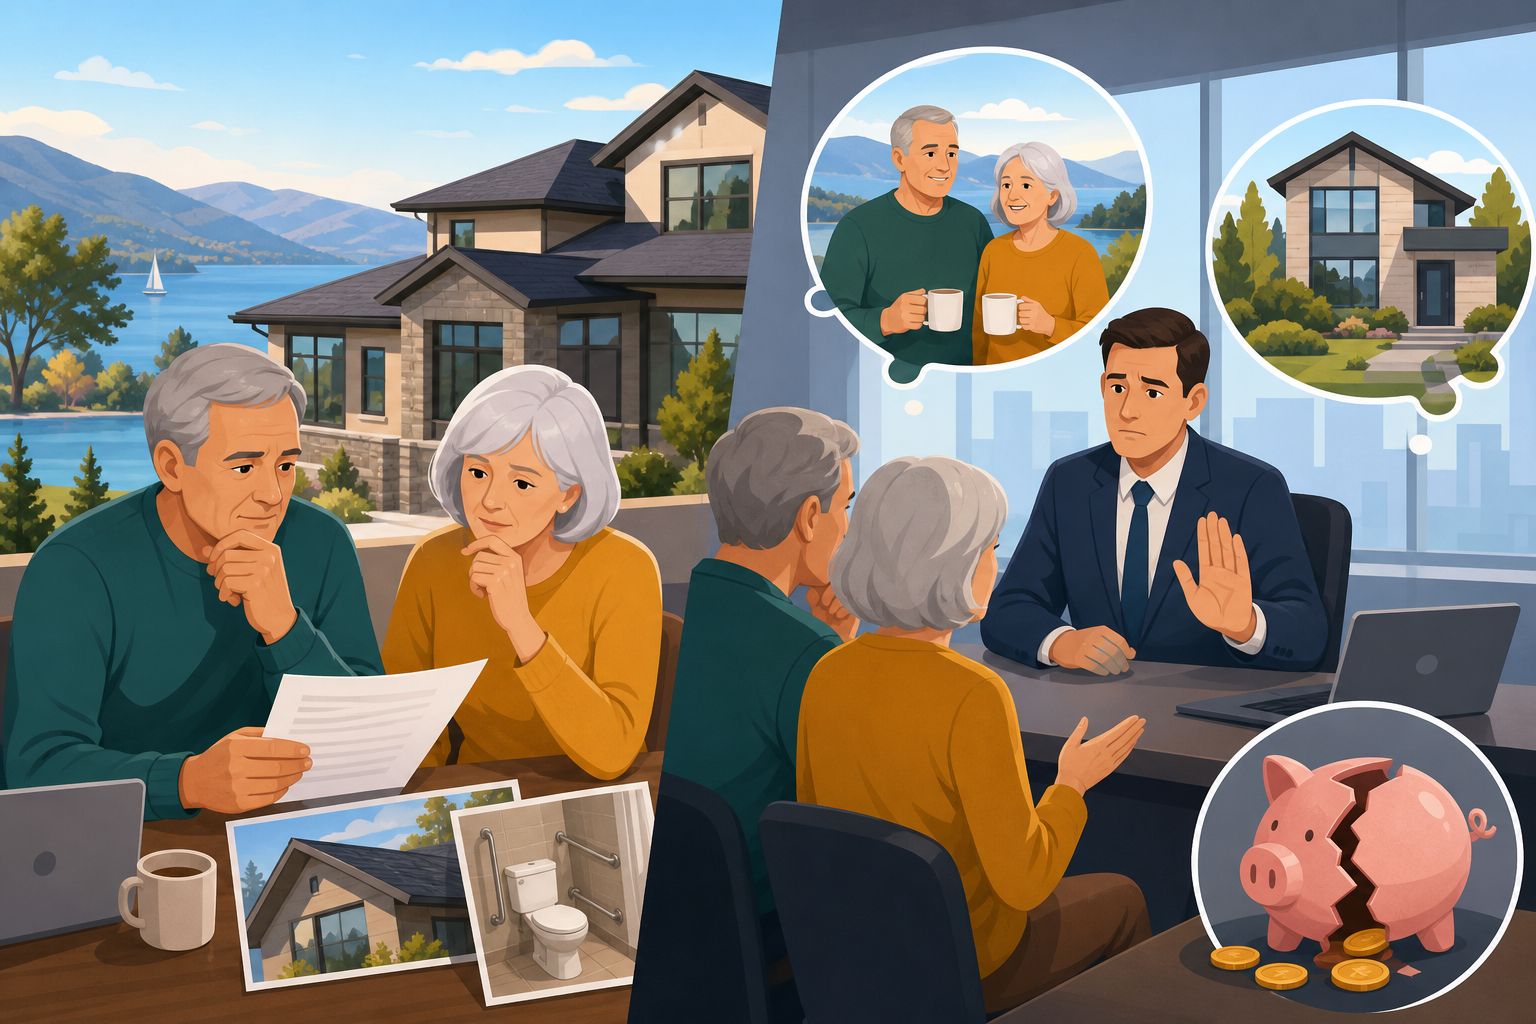

A Kelowna couple owns their home outright. $1.8 million in equity, no mortgage. The husband retires in March, and by June they need $75,000 to replace the roof and retrofit an accessible bathroom. They apply for a line of credit. The bank says no.
The rejection isn't about collateral. The house appraises fine. The couple simply no longer earns enough monthly income to pass the stress test, which requires them to qualify at 5.25% even though the actual rate is closer to 5.5%. Their CPP, OAS, and modest RRSP withdrawals total $4,200 a month. Under federal Debt Service Ratio rules, that's enough for about $40,000 of revolving credit. The bank assumed their equity would support $150,000.
A couple with monthly income of $4,200 can secure a $40,000 line of credit but not the $150,000 they expected. This happens because banks lend against the paycheque, not the house. You must act before the paycheque stops.
Banks lend against cash flow, not net worth
Canadian lenders qualify you on Gross Debt Service (GDS) and Total Debt Service (TDS) ratios. The stress test floor, currently 5.25%, means you must prove you could still afford the payments if rates spiked. A borrower earning $120,000 a year qualifies for far more credit than a retiree pulling $50,000 from pensions and registered accounts, even when the retiree has ten times the assets.
The Office of the Superintendent of Financial Institutions enforces this through its B-20 guidelines. The system is designed to protect borrowers from over-leverage, but it creates a paradox for asset-rich, income-light households. You can own a $2 million house free and clear and still fail to qualify for a $100,000 HELOC once your T4 income disappears.
The zero-cost safety net
A Home Equity Line of Credit costs nothing if you never use it. It sits at a zero balance, incurs no interest, and requires no monthly payment until you draw on it. The cost to set one up, legal fees, appraisal, registration, runs $800 to $2,000 depending on the lender and whether you're bundling it with a mortgage renewal. That's the full price of the insurance policy.
Federal rules cap the revolving portion of a HELOC at 65% of your home's value. On an $800,000 Kelowna home, that's $520,000 of potential access. Once registered, the limit stays in place regardless of what happens to your income, your job, or your health. The line remains open as long as you don't default or trigger a readvanceable mortgage clause that reduces the limit as you pay down a mortgage.
The best time to secure this is during a mortgage renewal or a purchase. Most lenders will register the charge as part of the transaction, which saves you a separate set of fees. If you're three years from retirement and refinancing anyway, this is when you lock it in.
What it actually buys you
The most common use isn't lifestyle spending. It's sequence-of-return protection. A retiree forced to sell equities in a down market to pay for a new furnace or property taxes locks in losses that compound over the rest of their retirement. A HELOC lets you cover the expense with borrowed funds, wait for the market to recover, then repay the line from the portfolio at a better valuation.
Estate planning is the other big one. Immediate estate costs, probate fees, final tax bills, property maintenance while the estate settles, often come due before the executor can liquidate RRSPs or investment accounts. A line of credit provides the liquidity to pay those bills without triggering a forced withdrawal at the worst possible tax rate.
Aging-in-place modifications are the third. Kelowna's housing stock skews older. A house built in 1985 wasn't designed for someone using a walker. Installing a stair lift, widening doorways, or retrofitting a main-floor bathroom runs $30,000 to $80,000. If you're already retired and living on $55,000 a year, most banks won't lend you that money. If you set up the line five years earlier, the money is already there.
The retirees who regret this decision are the ones who wait until they need the credit to apply for it. By then, the underwriter sees need as risk, and the application gets declined. The ones who sleep well are the ones who secured the line while they were still flourishing and let it sit unused for a decade.
Sources
Read Next
The OAS Clawback Is 15 Cents Per Dollar, Not 30 or 50
7 streaming services worth paying for in Canada, plus the credit cards that cut your bill
Ontario and B.C. First-Time Buyers Are Borrowing in Pairs, and the Cracks Are Starting to Show
Why Paying Off Your Mortgage First Can Cost You More Than the Interest Rate