How Rental Cash Flow Sequencing Can Accelerate Your Mortgage Payoff
Rent lands in your account on the first of the month, and the next transfer you make with it decides how many more years you'll carry your home mortgage. Most investors send it straight back out to the rental's own bills: property tax, insurance, strata fees, repairs. It feels tidy. It also leaves one of the largest tax advantages available to a Canadian landlord unused.
Two investors can own the same properties, carry the same mortgages and collect the same rent, and still finish years apart. The order in which they move cash decides which debt the government helps pay for. If you own a rental and still have a mortgage on your home in BC or Ontario, your current setup is already making that choice for you.
Deductibility follows what the borrowed dollar paid for
Under section 20(1)(c) of the Income Tax Act, interest is deductible when the borrowed money is used to earn income. The CRA looks at the direct use of the funds. Interest on your home mortgage fails that test. Interest on a loan that paid a rental's property tax or a furnace repair passes it, even if the rent that could have covered that bill went somewhere else first.
So the totals can be identical while the tax result is completely different. The sequence of transactions decides it.


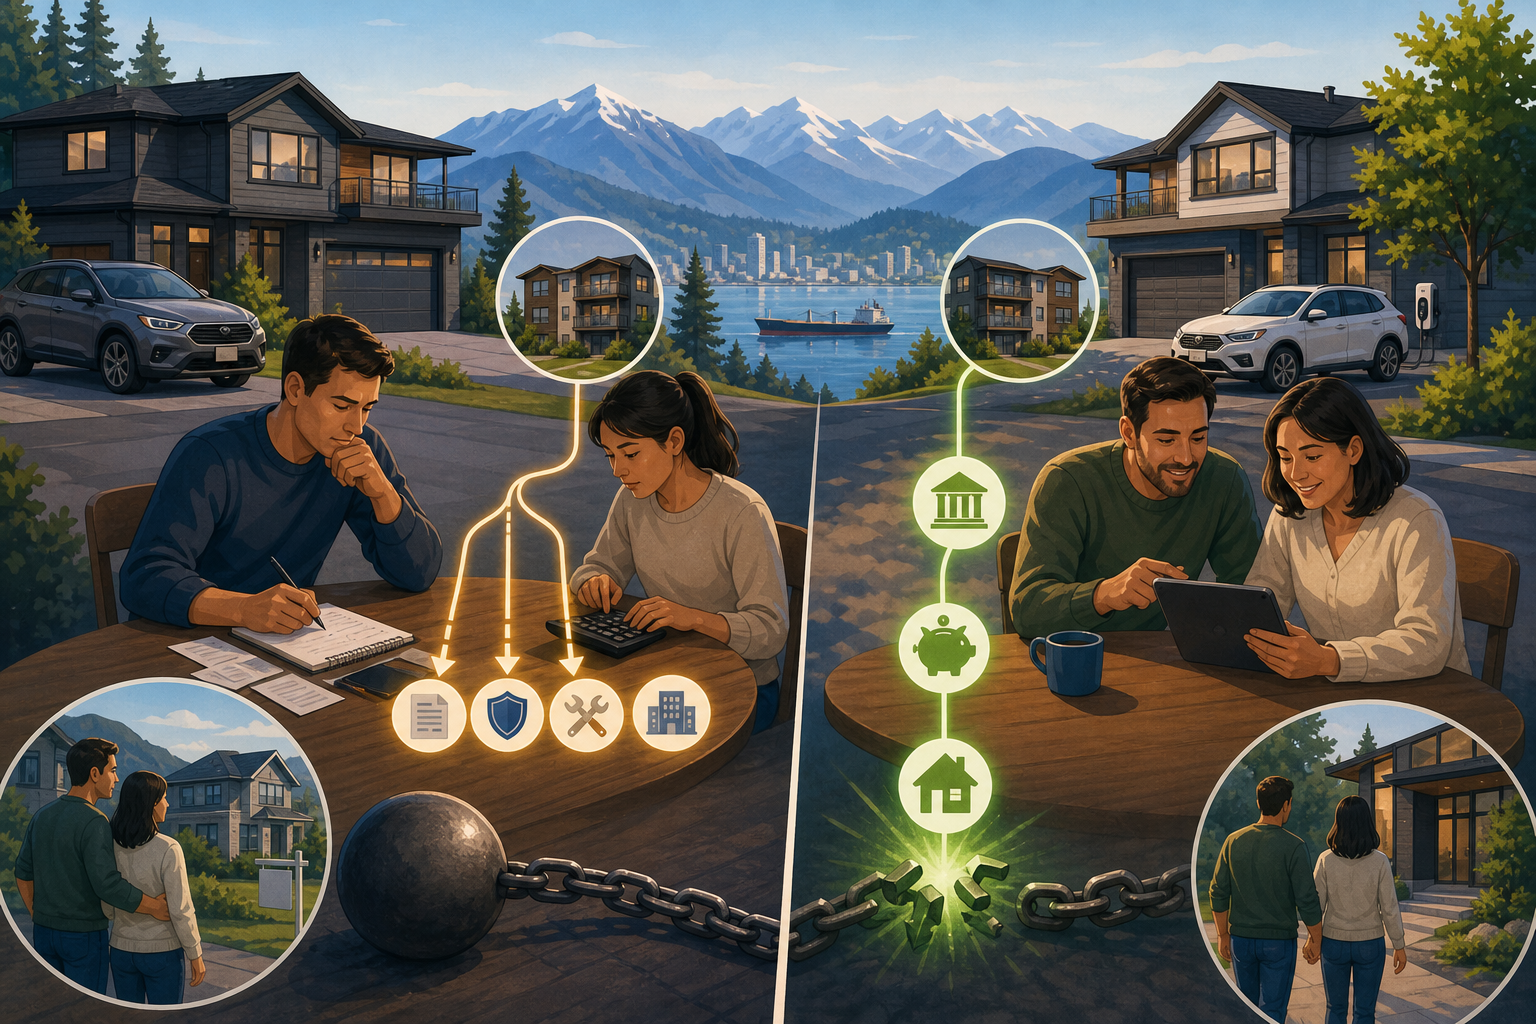

Rent lands in your account on the first of the month, and the next transfer you make with it decides how many more years you'll carry your home mortgage. Most investors send it straight back out to the rental's own bills: property tax, insurance, strata fees, repairs. It feels tidy. It also leaves one of the largest tax advantages available to a Canadian landlord unused.
Two investors can own the same properties, carry the same mortgages and collect the same rent, and still finish years apart. The order in which they move cash decides which debt the government helps pay for. If you own a rental and still have a mortgage on your home in BC or Ontario, your current setup is already making that choice for you.
Deductibility follows what the borrowed dollar paid for
Under section 20(1)(c) of the Income Tax Act, interest is deductible when the borrowed money is used to earn income. The CRA looks at the direct use of the funds. Interest on your home mortgage fails that test. Interest on a loan that paid a rental's property tax or a furnace repair passes it, even if the rent that could have covered that bill went somewhere else first.
So the totals can be identical while the tax result is completely different. The sequence of transactions decides it.
Same rent, two routes (ill
Sources
Read Next
Restructuring Your Mortgage Is Not a Rescue Mission
What a Mortgage Rate Discount Is Designed to Keep You From Noticing
Bank of Canada Cuts Won't Save Your Fixed Rate From U.S. Inflation
7 Debt Ratio Checks That Set Your Mortgage Ceiling Before Your Credit Score Matters