CRA Doesn't Care What Secures the Loan, Only Where the Cash Went
Pull $100,000 of equity out of a rental property, spend it on a truck, and the interest on that $100,000 is personal interest, even though the loan sits on a building that collects rent every month.
Most investors carry a sensible rule of thumb: rental mortgage, deductible interest; home mortgage, no deduction. For a straight purchase, it holds. You borrowed to buy the rental, the rental earns rent, and the interest goes on your rental statement. The rule breaks the moment you refinance, because a refinance creates fresh borrowed money with no purpose attached to it yet. Under paragraph 20(1)(c) of the Income Tax Act, interest is deductible when the borrowed money is used to earn income from a business or property. The building pledged as security never enters that test. Every dollar of equity you tap, on a rental or on your home, gets its tax status from where you spend it, and that status follows the loan for as long as you carry it.
Follow the dollar and ignore the deed
CRA traces. It wants to see the borrowed dollar leave the lender and arrive at something capable of producing income: a rental, a business, an investment that pays dividends or interest. The Supreme Court of Canada settled how strict this is in Singleton back in 2001, where the Court looked at the direct use of the borrowed money and set aside arguments about overall motive or how the arrangement looked.
The rule runs both ways. Equity borrowed against your Kelowna home and used as a down payment on an Ontario rental can be deductible. Equity borrowed against that same rental and spent on a kitchen at home is not. The same logic powers the Smith Manoeuvre™, which converts home mortgage debt into investment debt by re-borrowing and investing each dollar paid down. It works only because the use is traceable.
A mixed loan needs a split you can prove
Plenty of refinances do two jobs at once. As an illustration, say you take $100,000 out of a rental, put $60,000 toward a second property's down payment and spend $40,000 on personal items. Sixty percent of the interest on that $100,000 is deductible, and forty percent is not. CRA expects the apportionment to be consistent year after year and backed by records, so the split you claim in year one has to be the split you can still defend in year eight.
One chequing account can sink the whole claim
Here is where most deductions quietly die. Drop that $100,000 into the same chequing account that holds your paycheque and pays the hydro bill, and you've blended borrowed money with personal money. When the down payment leaves a week later, which dollars were they? Proving it becomes difficult, and an unprovable deduction is a denied one.
The fix is mechanical. Have refinance funds land in a separate account used for nothing else, or paid directly to the lawyer or the investment. Keep the statements for as long as the loan exists, well past CRA's usual six-year retention period, because the question of where the money went can come up any year you claim the interest.
The link can break after the fact
Deductibility is something you have to keep, too. Sell the investment and spend the proceeds personally, and the interest on the remaining loan generally stops being deductible. The money must also go into something with a reasonable expectation of income; you don't need a profit, but an asset that can only ever produce a capital gain invites a denial. Borrowing to pay your personal income tax bill, even tax that came from rental income, doesn't qualify either.
With a readvanceable mortgage requiring at least 20% equity and many BC and Ontario owners sitting well above that, the temptation to treat equity as one big pool is real. Equity has no tax character until you borrow it and spend it. Before the next draw hits your account, decide where every dollar is going, and set up the path so a stranger reading your bank statements could follow it from the lender to the income-producing asset without asking you a single question.


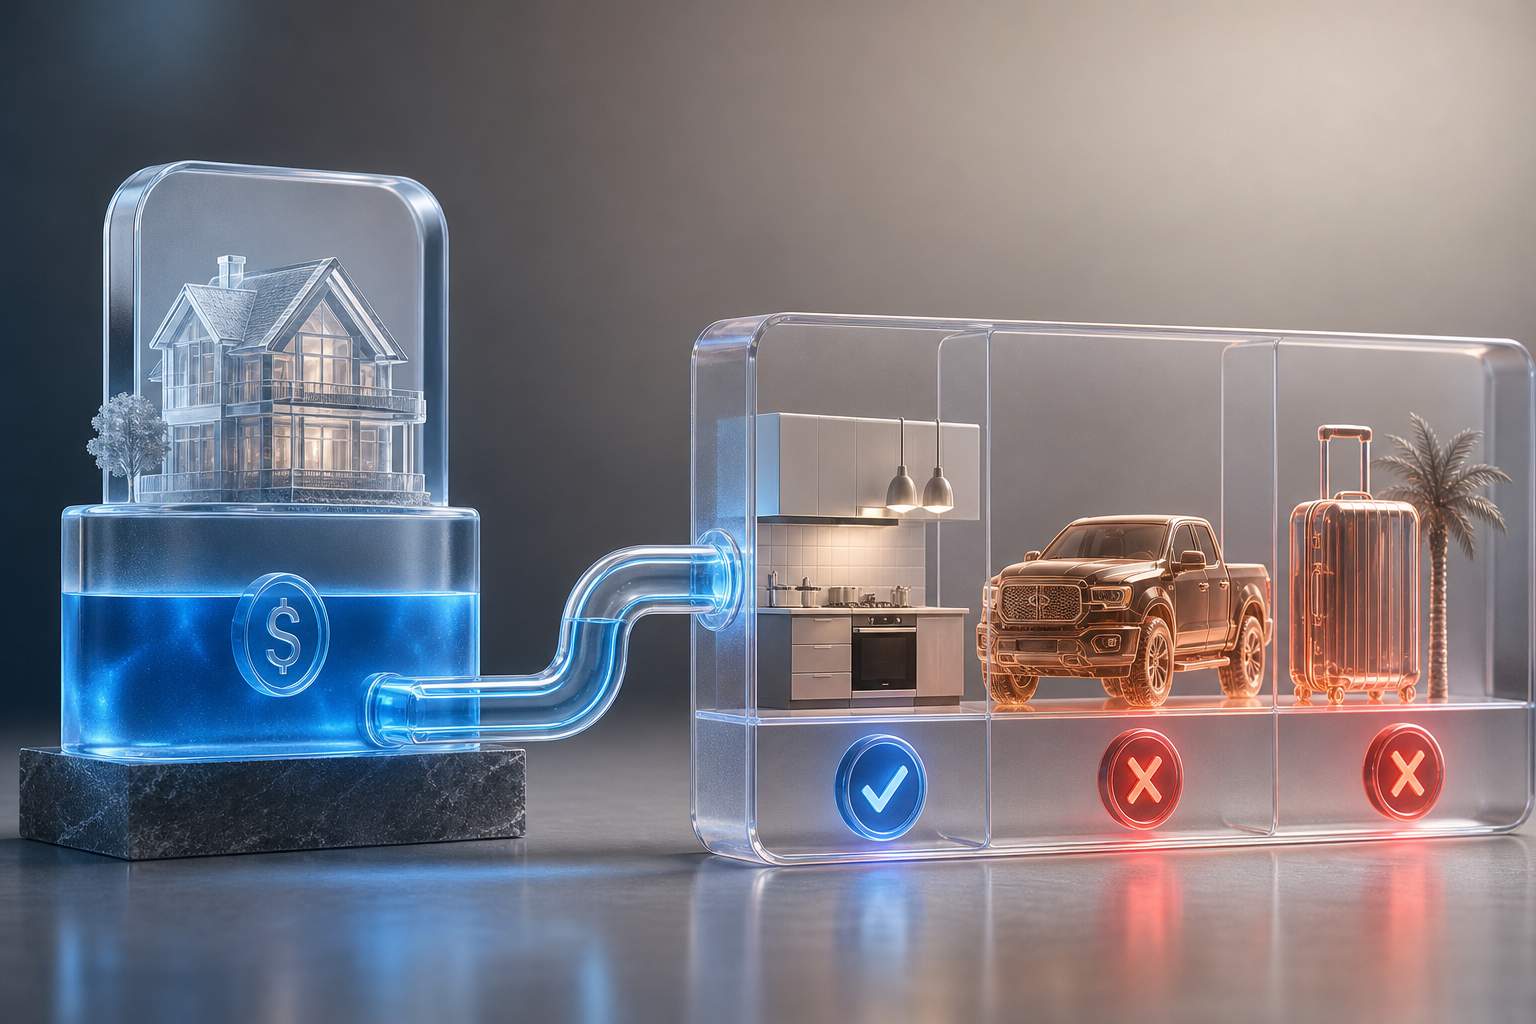

Pull $100,000 of equity out of a rental property, spend it on a truck, and the interest on that $100,000 is personal interest, even though the loan sits on a building that collects rent every month.
Most investors carry a sensible rule of thumb: rental mortgage, deductible interest; home mortgage, no deduction. For a straight purchase, it holds. You borrowed to buy the rental, the rental earns rent, and the interest goes on your rental statement. The rule breaks the moment you refinance, because a refinance creates fresh borrowed money with no purpose attached to it yet. Under paragraph 20(1)(c) of the Income Tax Act, interest is deductible when the borrowed money is used to earn income from a business or property. The building pledged as security never enters that test. Every dollar of equity you tap, on a rental or on your home, gets its tax status from where you spend it, and that status follows the loan for as long as you carry it.
Follow the dollar and ignore the deed
CRA traces. It wants to see the borrowed dollar leave the lender and arrive at something capable of producing income: a rental, a business, an investment that pays dividends or interest. The Supreme Court of Canada settled how strict this is in Singleton back in 2001, where the Court looked at the direct use of the borrowed money and set aside arguments about overall motive or how the arrangement looked.
The rule runs both ways. Equity borrowed against your Kelowna home and used as a down payment on an Ontario rental can be deductible. Equity borrowed against that same rental and spent on a kitchen at home is not. The same logic powers the Smith Manoeuvre™, which converts home mortgage debt into investment debt by re-borrowing and investing each dollar paid down. It works only because the use is traceable.
A mixed loan needs a split you can prove
Plenty of refinances do two jobs at once. As an illustration, say you take $100,000 out of a rental, put $60,000 toward a second property's down payment and spend $40,000 on personal items. Sixty percent of the interest on that $100,000 is deductible, and forty percent is not. CRA expects the apportionment to be consistent year after year and backed by records, so the split you claim in year one has to be the split you can still defend in year eight.
One chequing account can sink the whole claim
Here is where most deductions quietly die. Drop that $100,000 into the same chequing account that holds your paycheque and pays the hydro bill, and you've blended borrowed money with personal money. When the down payment leaves a week later, which dollars were they? Proving it becomes difficult, and an unprovable deduction is a denied one.
The fix is mechanical. Have refinance funds land in a separate account used for nothing else, or paid directly to the lawyer or the investment. Keep the statements for as long as the loan exists, well past CRA's usual six-year retention period, because the question of where the money went can come up any year you claim the interest.
The link can break after the fact
Deductibility is something you have to keep, too. Sell the investment and spend the proceeds personally, and the interest on the remaining loan generally stops being deductible. The money must also go into something with a reasonable expectation of income; you don't need a profit, but an asset that can only ever produce a capital gain invites a denial. Borrowing to pay your personal income tax bill, even tax that came from rental income, doesn't qualify either.
With a readvanceable mortgage requiring at least 20% equity and many BC and Ontario owners sitting well above that, the temptation to treat equity as one big pool is real. Equity has no tax character until you borrow it and spend it. Before the next draw hits your account, decide where every dollar is going, and set up the path so a stranger reading your bank statements could follow it from the lender to the income-producing asset without asking you a single question.
Read Next
Restructuring Your Mortgage Is Not a Rescue Mission
What a Mortgage Rate Discount Is Designed to Keep You From Noticing
Bank of Canada Cuts Won't Save Your Fixed Rate From U.S. Inflation
7 Debt Ratio Checks That Set Your Mortgage Ceiling Before Your Credit Score Matters