CPP and OAS at 65 or 70: How Chronic Illness Changes the Math
Raj has type 2 diabetes and osteoarthritis. He's 64, still working part-time as an electrician, and trying to decide whether to start his Canada Pension Plan now or wait until 70. His doctor says his conditions are manageable but will cost him about six years of life expectancy versus the average Canadian male. That six-year number changes everything.
The standard advice is to delay. Wait until 70 and CPP jumps 42% above the age-65 amount, 0.7% for every month you hold off. Old Age Security adds 36% if you push to 70. The math works if you live past 82 to 83. For someone with a shortened runway, that breakeven age might arrive after they're gone.
The Longevity Bet You're Actually Making
Start with what delaying costs in cash terms. A 65-year-old taking the average CPP of $925/month collects $55,500 by age 70. The person who waits gets zero during those five years, then starts at $1,314/month. To recover that $55,500 gap, they need to live to roughly 77. Add another five years to break even on total cumulative value, accounting for inflation adjustments on both paths. That puts the crossover between 77 and 82, depending on tax treatment and the actual CPI path.
Raj's doctor says expect 77, maybe 79. The "win" from delaying is now a coin flip, and the cost of being wrong is five years of income he never collected.
Where this gets more precise: chronic illness doesn't always mean shorter life. Managed diabetes that doesn't lead to cardiovascular disease or renal failure may only shave two to three years off. Severe COPD or late-stage heart failure can cut a decade. The decision splits on whether your condition is managed-but-stable or progressive-and-accelerating.
When Early Beats Late Even for the Healthy
The breakeven calculation assumes you're spending the early money and investing the late money equally, which almost no one does. In practice, people who take CPP at 65 often use it to avoid drawing down their RRIF, letting that account grow tax-deferred for another five years. People who delay to 70 are usually pulling harder from their RRIF in their 60s, triggering tax and potentially losing Guaranteed Income Supplement eligibility if income crosses the threshold.
For a chronically ill person with a $320,000 RRIF, the math can flip: take CPP early, preserve the RRIF, and reduce the tax bomb on death. RRIFs left to heirs face terminal taxation at rates up to 54% in some provinces. CPP paid out over 15 years instead of 10 has already moved money from a taxable estate into cash in hand.
The GIS trap is real for lower-income seniors. Delaying CPP to 70 can push total income above the $22,512 threshold where GIS gets clawed back. A single senior receiving maximum GIS in 2026 gets roughly $13,478 annually. Losing that to gain a higher CPP can be a net loss in total government transfers.
The CPP Disability Door Closes at 60
If you take early retirement CPP at 60 and your health worsens, you cannot switch to CPP Disability. The disability benefit often pays more than early retirement CPP, typically $1,210 to $1,741/month versus the reduced amount you locked in at 60. If your condition qualifies as preventing "substantially gainful" work, file for disability first. You can always switch to retirement CPP later. The reverse does not work.
OAS is simpler: you cannot start before 65. The decision is delay or don't, with no disability alternative.
Where the Advice Reverses
Chronic illness that's stable and managed but not immediately life-limiting creates the opposite problem. A 65-year-old with controlled rheumatoid arthritis might live to 85 but face higher care costs throughout. For that person, delaying OAS to 70 provides inflation-indexed income during the expensive final decade, when private savings may be depleted.
The rule: if the condition shortens life expectancy below 80, take it early. If the condition raises costs without shortening life, delay for the income insurance. If you don't know which, take it at 65.


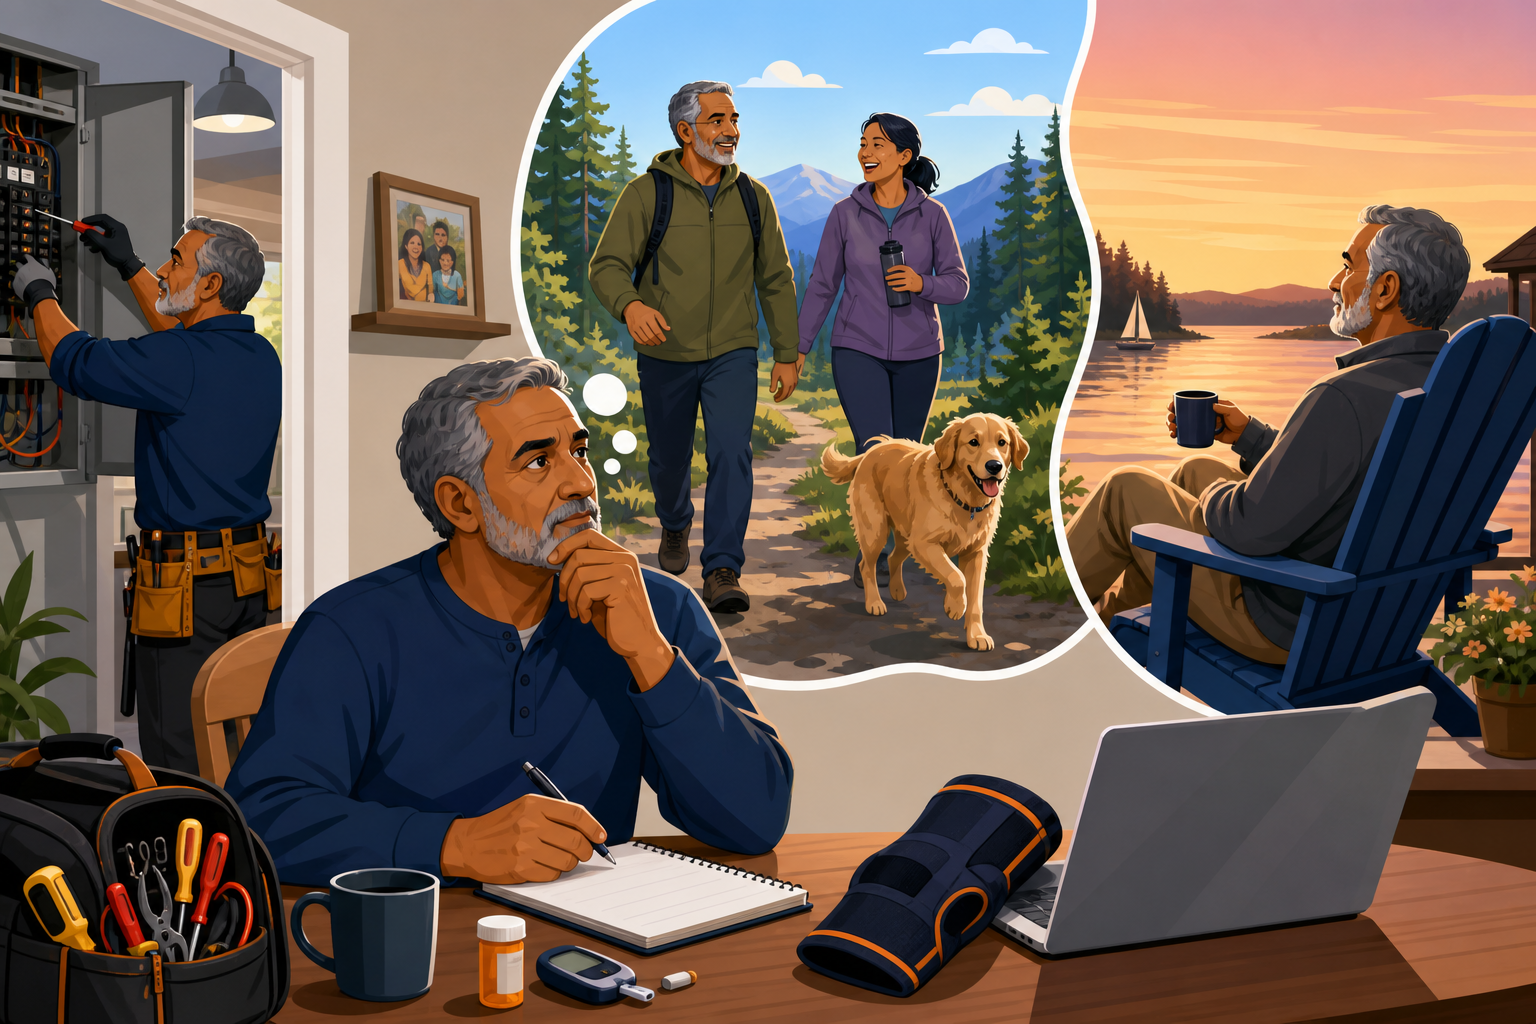

Raj has type 2 diabetes and osteoarthritis. He's 64, still working part-time as an electrician, and trying to decide whether to start his Canada Pension Plan now or wait until 70. His doctor says his conditions are manageable but will cost him about six years of life expectancy versus the average Canadian male. That six-year number changes everything.
The standard advice is to delay. Wait until 70 and CPP jumps 42% above the age-65 amount, 0.7% for every month you hold off. Old Age Security adds 36% if you push to 70. The math works if you live past 82 to 83. For someone with a shortened runway, that breakeven age might arrive after they're gone.
The Longevity Bet You're Actually Making
Start with what delaying costs in cash terms. A 65-year-old taking the average CPP of $925/month collects $55,500 by age 70. The person who waits gets zero during those five years, then starts at $1,314/month. To recover that $55,500 gap, they need to live to roughly 77. Add another five years to break even on total cumulative value, accounting for inflation adjustments on both paths. That puts the crossover between 77 and 82, depending on tax treatment and the actual CPI path.
Raj's doctor says expect 77, maybe 79. The "win" from delaying is now a coin flip, and the cost of being wrong is five years of income he never collected.
Where this gets more precise: chronic illness doesn't always mean shorter life. Managed diabetes that doesn't lead to cardiovascular disease or renal failure may only shave two to three years off. Severe COPD or late-stage heart failure can cut a decade. The decision splits on whether your condition is managed-but-stable or progressive-and-accelerating.
When Early Beats Late Even for the Healthy
The breakeven calculation assumes you're spending the early money and investing the late money equally, which almost no one does. In practice, people who take CPP at 65 often use it to avoid drawing down their RRIF, letting that account grow tax-deferred for another five years. People who delay to 70 are usually pulling harder from their RRIF in their 60s, triggering tax and potentially losing Guaranteed Income Supplement eligibility if income crosses the threshold.
For a chronically ill person with a $320,000 RRIF, the math can flip: take CPP early, preserve the RRIF, and reduce the tax bomb on death. RRIFs left to heirs face terminal taxation at rates up to 54% in some provinces. CPP paid out over 15 years instead of 10 has already moved money from a taxable estate into cash in hand.
The GIS trap is real for lower-income seniors. Delaying CPP to 70 can push total income above the $22,512 threshold where GIS gets clawed back. A single senior receiving maximum GIS in 2026 gets roughly $13,478 annually. Losing that to gain a higher CPP can be a net loss in total government transfers.
The CPP Disability Door Closes at 60
If you take early retirement CPP at 60 and your health worsens, you cannot switch to CPP Disability. The disability benefit often pays more than early retirement CPP, typically $1,210 to $1,741/month versus the reduced amount you locked in at 60. If your condition qualifies as preventing "substantially gainful" work, file for disability first. You can always switch to retirement CPP later. The reverse does not work.
OAS is simpler: you cannot start before 65. The decision is delay or don't, with no disability alternative.
Where the Advice Reverses
Chronic illness that's stable and managed but not immediately life-limiting creates the opposite problem. A 65-year-old with controlled rheumatoid arthritis might live to 85 but face higher care costs throughout. For that person, delaying OAS to 70 provides inflation-indexed income during the expensive final decade, when private savings may be depleted.
The rule: if the condition shortens life expectancy below 80, take it early. If the condition raises costs without shortening life, delay for the income insurance. If you don't know which, take it at 65.
Sources
Read Next
The OAS Clawback Is 15 Cents Per Dollar, Not 30 or 50
7 streaming services worth paying for in Canada, plus the credit cards that cut your bill
Ontario and B.C. First-Time Buyers Are Borrowing in Pairs, and the Cracks Are Starting to Show
Why Paying Off Your Mortgage First Can Cost You More Than the Interest Rate